

Earnings insights for US & Canadian micro- & small-caps (less than $2B mkt cap). By @majgeoinvesting & @SebKrog
Joined January 2026
- Tweets142
- Following58
- Followers1.2K
- Likes147
EPSMonitor retweeted

Get ready for the third-quarter small and microcap earnings season. Many stocks with great earnings reports have pulled back during the last few weeks. That’s precisely the time to be more aggressive in research, when some people have temporarily given up.

Every month @SebKrog & @majgeoinvesting hold a live virtual event, going over the best and most interesting smaller-cap earnings reports during the last few weeks, as well review past reports getting more of our attention. Learn more at our Substack - where events are archived.

EPSMonitor retweeted
At first glance, this one looks really interesting. Worth diving into. I’ll be spending lots of time going through these earnings cards on @EPSMonitor, ahead of the third-quarter small and microcap earnings season.
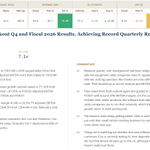
$VCM.TO — Breakout Q4: record revenue up 36% to C$91M, EBITDA more than tripled to C$18.9M. Gross margin jumped from 26% to 45%. EPS swung from a C$0.55 loss to C$0.22 profit.
Guided FY2027 revenue growth of 30-35% with ~20% EBITDA margins. Trading at 7.1x FY+1 P/E. Mgmt says their newer software products are barely included in guidance and could be a bigger driver in 2028+.

EPSMonitor retweeted
Second quarter earnings reports are around the corner. You can use our small-cap monitor to make your research more efficient by focusing on the reports that are actually worth your time.
smallcapearningsmonitor.subs…
EPSMonitor retweeted
🔴 LIVE THIS THURSDAY (May 28)
- 10 small-cap picks in one session, 5 from @majgeoinvesting, 5 from @SebKrog
- Live on Substack. Open to everyone. Tickers named on stream.
🕐 Thursday, 12:30 PM ET
📍 Substack Live
Set a reminder 👇
EPSMonitor retweeted

✅Peter Lynch popularizó el concepto de los “baggers”:
compañías capaces de multiplicarse varias veces desde el precio de compra inicial.
El problema es que los grandes baggers rara vez aparecen en las compañías más seguidas del mercado.
Suelen aparecer en small caps poco conocidas, fuera del consenso y con catalizadores reales.
Durante los últimos dos años, compañías presentes en Equity Small Caps FI como:
Anterix, PaySign, Helios Towers, Vox Royalty, LandBridge, Amerigo Resources, Andean Precious Metals, Tasmea, Talkspace, REV Group, AltynGold, Dundee Precious Metals, Hanza o ISS
han llegado a subir más de un +100% desde niveles de entrada del fondo.
Algunas de ellas ya no forman parte de la cartera tras materializar gran parte del valor.
Otras siguen actualmente en cartera.
Muchas eran prácticamente desconocidas para la mayoría del mercado hace pocos meses o años.
Porque para encontrar baggers primero hay que atreverse a mirar donde casi nadie mira.
Precisamente ese es el enfoque de Equity Small Caps FI.
Informe completo en Rankia:
rankia.com/blog/fondos-inver…

EPSMonitor retweeted

$MAL.TO sits in the aerospace theme that we love… it’s a money direct and indirect theme.. Think MultiBaggers, like… $FTG.TO $TATT $FEIM
Weekly Earnings Brief #17 was published yesterday, featuringuring $MAL.TO, $FENC and others.
$MAL.TO (Aerospace Systems & Components): Magellan posted Q1 revenue up 9.3% YoY to 285M. Gross margin expanded 130bps to 14.2%, net income climbed 53% to 16.5M.
Defence mix is increasing as NATO targets move from 2% to 5% GDP. Boeing and Airbus have 10-year backlogs, giving the commercial segment strong visibility. Feb 2026 TKMS teaming agreement positions Magellan in Canada's Patrol Submarine torpedo program.
Global defence spending forecast: $2.6T in 2026, $2.9T by 2030.

EPSMonitor retweeted
$SIF Q1 earnings were completely under appreciated
• Aerospace theme with program funding accelerating
• Inflects to profitability after yrs of losses
• Aggressive backlog growth as sales grow
• Crazy operating leverage at the gross margin / OPEX level
• Run-Rate P/E = 10x
EPSMonitor retweeted
$ACFN Q1 2026 results were lackluster, and Q2 2026 will probably be a down quarter.
However, the AIO partnership is looking increasingly interesting. In the 10Q we got some interesting information about the software revenue split:
"The applicable share is initially 50%, and is reduced to 43% once cumulative amounts paid to AIO under this provision exceed $2.0 million, and further reduced to 34% once cumulative amounts paid exceed $4.0 million. Amounts due are to be calculated and remitted on a quarterly basis."

EPSMonitor retweeted
This sums up what we like about our next multibagger cliff note in the works:
“You don't need a lot to go right.”
EPSMonitor retweeted

Our team has published a research note on Cleantek Industries Inc. (TSXV: CTEK). CTEK reported solid financials, with Q4 and 2025 revenue coming in at $3.4M (+17% YoY) and $13.8M (+17% YoY), respectively, compared to our estimates of $4.2M and $14.5M. $CTEK.V
🔍 Read the full report below!
📰 Disclosure: Disseminated on Behalf of Cleantek Industries

EPSMonitor retweeted

1: $HAI.TO Deep Dive: Haivision is the ultimate Haas-Saas business - key to both defence and entertainment. Hard to find a business whose customer list boasts of: Facebook, Airbus, JP Morgan, NASA/SpaceX, US Navy, CNN/Warner Bros.
Stock had quite the run-up early this year but has given up most of its gain. At $6.6, the stock is basically trading at 8.6x FY26 EBITDA and the r/r looks very attractive (limited downside imo).

EPSMonitor retweeted

Instead of digging through the release and trying to pull the details - you can simply spend 30s reading the tweet below.
$CTEK.V CLEANTEK Industries is up ~20% today. We added this name to Brief #3 because of their strong 2026 guidance: $21.5-22.5M in revenue and $7.2-7.5M in EBITDA, driven by higher fleet utilization and international product sales.
The HALO SE contract signed in January should drive strong Q2 and Q3 as equipment deliveries ramp up.
If you've been reading the briefs, this was already on your radar.
@Atrium_Research also covers Cleantek

EPSMonitor retweeted
Weekly Update #10 is live. 2 microcap moves worth knowing about this week:
$ICCC Reported preliminary Q1 2026 sales of $10.4M, up 28% YoY. The bigger deal: the high-cost R&D segment that was dragging them down is gone. 2026 will be their first clean shot at profitability.
$IFA.TO / $IFABF We went into the Q4 conference call worried. A monster Q1 had been telegraphed, and we expected it to eclipse the rest of the year.
The call didn't just ease that concern. It made us more bullish.
Full breakdown below👇
mscliffnotes.substack.com/p/…
EPSMonitor retweeted
$RX.V should probably be added to our microcap quality index.
$RX.V has been a success story in the Microcap space. A 100-Bagger since 2011. Now, after an acquistion it might get interesting again. @majgeoinvesting shared his views here:

EPSMonitor retweeted
It's a crime to have this content for free.
Such a time saver, and insane value.
