

Ameya Deosthali differentiated insights for value investing Business Enquiries : [email protected]
earth
Joined August 2024
- Tweets11.4K
- Following82
- Followers23.5K
- Likes11.4K





Pinned Tweet
My take on position sizing , very less spoken about when it comes to process building
Understanding this opens up lot more non linearity of gains


ValueEquity retweeted
Ramkrishna Forgings , Delhivery & IEX call notes coming tomorrow , really happy with the way earnings season has been going so far
RKF , Laurus and Indegene have made me happiest this season , you will see many popular momentum chasing accounts starting to tweet on Indegene and RKF give it two days , thats why covering it when no one was gives me more delight , and you all know it !
Lot of notes and research coming tommorow and over the next week folks
ValueEquity retweeted
Ramkrishna Forgings , numbers now proving the thesis we had built 😀
Disc : biased , no reco ,

Ramkrishna Forgings — Q2FY27 Results 🔔
#Q2Results #Q2FY27 #Ramkrishna
Revenue ₹1405.42 Cr vs ₹907.53 Cr
(+54.86% YoY┃+15.51% QoQ)
EBITDA ₹256.23 Cr vs ₹122.55 Cr
(+109.08% YoY┃+17.28% QoQ)
EBITDA Margin 18.23% vs 13.50% YoY & 17.96% QoQ
PBT +₹95.46 Cr vs -₹10.27 Cr YoY & +₹64.73 Cr QoQ
(+47.47% QoQ)
PAT +₹70.59 Cr vs -₹9.50 Cr YoY & +₹46.88 Cr QoQ
(+50.58% QoQ)
Other Income ₹4.20 Cr vs ₹5.75 Cr YoY & ₹3.44 Cr QoQ

Ramkrishna Forgings , numbers now proving the thesis we had built 😀
Disc : biased , no reco ,
Ramkrishna Forgings — Q2FY27 Results 🔔
#Q2Results #Q2FY27 #Ramkrishna
Revenue ₹1405.42 Cr vs ₹907.53 Cr
(+54.86% YoY┃+15.51% QoQ)
EBITDA ₹256.23 Cr vs ₹122.55 Cr
(+109.08% YoY┃+17.28% QoQ)
EBITDA Margin 18.23% vs 13.50% YoY & 17.96% QoQ
PBT +₹95.46 Cr vs -₹10.27 Cr YoY & +₹64.73 Cr QoQ
(+47.47% QoQ)
PAT +₹70.59 Cr vs -₹9.50 Cr YoY & +₹46.88 Cr QoQ
(+50.58% QoQ)
Other Income ₹4.20 Cr vs ₹5.75 Cr YoY & ₹3.44 Cr QoQ
ValueEquity retweeted
Indegene , slowly all the attention will come ..., wait for that 19% H2 EBITDA, you are seeing already how suddenly many are talking about it today on the back of strong numbers
ValueEquity retweeted
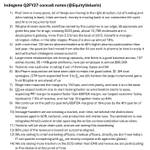
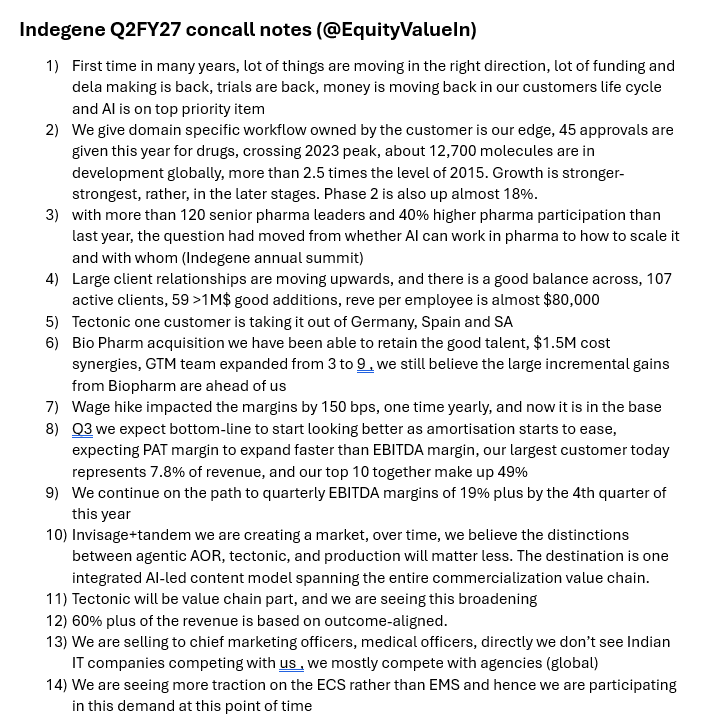
Indegene Q2FY27 concall notes , my notes from the call concluded earlier this morning
H2 EBITDA margin comeback will be there (4Q heavy) , customers level growth , funding and market is back , bio pharm GTM team ahs seen good additions , expecting PAT flowthrough to start in Q3 and increase in Q4 , cost base for hikes is fully in this Quarter
disc: biased , no reco , do your research , take opinion with pinch of salt
If you outsource conviction and research to AI , you will be disappointed , because when stock falls 20% after buying the model will reprice its estimates ,but you will be stuck thinking how to manage the situation , but courage can never be outsourced
Intuition , Courage , ability to survive , can never be outsourced
Use AI as a tool to make your edge better , not to be the edge itself , because it never can
Indegene Q2FY27 concall notes , my notes from the call concluded earlier this morning
H2 EBITDA margin comeback will be there (4Q heavy) , customers level growth , funding and market is back , bio pharm GTM team ahs seen good additions , expecting PAT flowthrough to start in Q3 and increase in Q4 , cost base for hikes is fully in this Quarter
disc: biased , no reco , do your research , take opinion with pinch of salt
Indegene , slowly all the attention will come ..., wait for that 19% H2 EBITDA, you are seeing already how suddenly many are talking about it today on the back of strong numbers
Laurus Labs Q2FY27 , Aarti Pharmalabs and Styrenix Performance , my latest audio note on substack , discussing my opinions and thoughts on the latest numbers and updates
substack.com/@valueequityin/…

Laurus Labs , the Iceberg CDMO business is here , what a great journey it has been over the past 2 years , Dr Sathya has executed flawlessely and we have been participants with him and the team in the Journey
2 years back , when I had written below in Sep-24 on the iceberg business at Laurus , and today it is here , thesis has played out beautifullly , especially considering market structure
no reco, biased from much lower levels


Coforge at new life highs 😀, against all odds , the man in the arena as I’d like to call it
Now today no one talking about resignations noise or IT pessimism
Peak pessimism when turns , turns very fast , happy with work done here over last 8 months
Disc: no reco , biased from lower levels
Indegene good numbers 😀, my notes and thoughts tomorrow!
Overall top line and EBITDA growth is good, we should start seeing bottom line growth from next Q
No reco
ValueEquity retweeted
Laurus Labs Q2FY27 , Aarti Pharmalabs and Styrenix Performance , my latest audio note on substack , discussing my opinions and thoughts on the latest numbers and updates
link : substack.com/@valueequityin/…

Laurus Labs Q2FY27 , Aarti Pharmalabs and Styrenix Performance , my latest audio note on substack , discussing my opinions and thoughts on the latest numbers and updates
link : substack.com/@valueequityin/…
ValueEquity retweeted
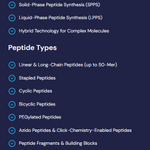
Laurus Labs Q2FY27 concall notes , my notes from the call just concluded
Strong numbers , Peptides capex , and on new acqusitions and what lies ahead
no reco , biased from much lower levels


Laurus Labs Q2FY27 concall notes , my notes from the call just concluded
Strong numbers , Peptides capex , and on new acqusitions and what lies ahead
no reco , biased from much lower levels
Indiamart , avoiding few businesses also adds to the alpha , I remember in Jan there was so much hype around a fund entering and more , and everyone was calling it structural story , stock is down more than 30%
Avoided this one as signs were clear ! and has worked out well, see below tweet after the popular deal when I had written about headcount reduction as well
Some balls outside off always better to leave!
India Mart actually reduced headcount for the first time in a long time and business enquiries are down , and I'm not too sure how to evaluate their investments book , so currently I am staying away , yes I know Nalanda entered , but I don't think this suits my way of investing , leaving this ball , may go wrong , but okay with it !

ValueEquity retweeted
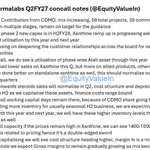
Aarti PharmaLabs Q2FY27 concall notes , my notes from the call just ended
CDMO guidance intact , Xanthine phase wise scale up over the next yera , Q3 expect some capitalisation and depriciation costs , margins we expect to improve as mix gets better and expecting R&D Trends to accelerate , more notes below , detailed thoughts on substack audio note in the evening , if you haven't already , do follow it
substack.com/@valueequityin
no reco , biased from lower levels