






Pinned Tweet
@RealJimChanos says $IREN bulls should stop leaning on ARR, $/MW and prepayments and look at the actual accounting.
So I did.
It got more bullish.
At June 30, IREN disclosed ~$5.1B of ASC 606 remaining performance obligations plus ~$11.4B of contracted arrangements under ASC 842.
That’s ~$16.6B of contractual obligations in the financial statements.
Then ~$2.8B of new contracts were signed in July.
Before assigning anything to the unnamed frontier AI lab announced in August, I can identify >$19.4B of contracted obligations.
I’m intentionally not calling all of that “backlog.” Different accounting, different durations.
That’s the point: you don’t need the ARR slide to find the demand.
The contracts are in the filings.
IREN also ended June with $1.84B of deferred revenue. Roughly $1.62B was advance payments on lease-accounted tranches that hadn’t even commenced.
Not profit.
Customer cash arriving BEFORE the asset starts producing revenue.
And this is where I think the dilution argument starts to break.
For Microsoft/Horizons:
~$3.6B of investment-grade GPU financing + ~$1.9B of Microsoft prepayments against a ~$5.8B GPU purchase agreement.
~95–96% of associated GPU capex funded.
For Mackenzie, the $2.4B financing alone funds ~90% of associated GPU capex.
Customer prepayments sit on top, pushing total GPU-linked funding above GPU cost and helping fund data-center capex.
Now FY27:
$25–30B capex.
~$14B existing cash + committed GPU financing/prepayments.
~$8B additional GPU financing/prepayments targeted.
That leaves a $3–8B gross residual BEFORE data-center financing and operating cash flow.
Meanwhile management says 100% of its data-center portfolio remains unencumbered — including Horizons 1–4, the 300MW gross / ~200MW IT Childress build supporting a $9.7B Microsoft contract.
Think about that structure.
The Microsoft compute layer is already ~95–96% funded.
The data-center layer is still available to finance.
So the first DC financing doesn’t have to solve a $30B problem.
It attacks the remaining $3–8B residual.
In the favorable end of my funding bridge, DC financing + ex-prepayment operating cash flow can take that residual close to zero before incremental common equity.
I’m not making that my base case yet.
But it’s a very different setup from “IREN needs to issue $30B of stock.”
Customer prepay → GPU debt → operating asset → DC financing/refi → recycle capital.
That’s the flywheel.
The point isn’t zero dilution.
It’s that common equity can become the residual funding rail instead of the primary one.
Now Chanos’ ARR/revenue point.
How can IREN target >$4B of operational ARR at Dec. 31 while sell-side FY27 revenue is only ~$2.5B?
FY27 runs July through June.
Dec. 31 is halfway through it.
The >$4B is the annualized rate of the operating fleet at that point. The first half is the ramp.
Different clocks. No contradiction.
His capex comparison has the same issue.
FY27 capex funds multiple vintages: finishing CY26, CY27 air-cooled deployments, major DC construction for H2-CY27 Childress/Sweetwater, plus early CY28+ work.
The GPUs for those new H2-CY27 liquid-cooled facilities aren’t even in the FY27 guide.
A multi-vintage construction budget divided by one earlier vintage of ARR will obviously make returns look bad.
The numerator and denominator aren’t the same assets.
One Chanos point I’ll give him (cont.)


Tree retweeted

The market is punishing neoclouds after the Magnificent Seven earnings, even though all the CEOs are telling us they don’t have enough compute capacity to meet demand. Google literally told us yesterday that it began using third-party compute capacity at the end of Q3 and plans to increase usage in Q4, even though that will put pressure on its margins.
Think about that for a second. This multi-trillion-dollar company is willing to accept lower margins to secure more compute so it can serve more customers and generate more revenue. They see it as a necessity. For the companies that can supply that capacity on time, I see this as very bullish.
Tree retweeted

I get why you want to punish the hyperscalers for their CapEx, but why punish the suppliers at the same time?
That doesn’t make sense to me
100% public markets are dumb right now and will get smart quick soon. $IREN thesis has only gotten better. Criminally cheap.

.@GavinSBaker on neolabs pivoting into neoclouds:
"If you signed a long-term compute contract at any point prior to May of 2026, you are way in the money. You're buying compute for $10 or $15 a watt. And you could sell it at a massive premium to that price today."
"And it's not just that the spot market is tight today. You have to pay vast amounts to bring on a cluster in mid- to late-2027."
"I think that's something that public markets are not appreciating... All [this information] is out there, but for whatever reason, I think it's not legible to the public markets."
$IREN This is an Iren tweet.

Tree retweeted

It means companies like $IREN stand to take over the world 😈


I think it’s time to fall back to this post for anyone feeling nervous on $IREN Take the time to read it and feel better. Much better days ahead. If you want to be a good investor then you better be prepared for moments like these. Hang in there.

$IREN
I did something with my IREN model this week that I’ve intentionally avoided for a while.
I stopped asking:
“What can I underwrite with high confidence today?”
And asked a different question:
What does IREN look like if most of the things already in motion simply work?
I expected the answer to require some pretty stupid assumptions.
It didn’t.
My normal model is intentionally conservative.
Unsigned contracts don’t get full credit. Future capacity is discounted. I don’t assume Rubin economics before they’re proven.
And I count the debt, dilution and replacement costs.
That’s how I get to roughly $50/share today.
For this exercise I changed the question, not the discipline.
No faster timelines.
No $30M/IT-MW assumption.
No 6-year GPU life.
No NVIDIA financing backstop.
No Mirantis software multiple.
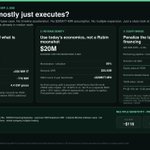
I mostly let IREN execute.
IREN is already targeting 0.8GW IT in CY27.
My high-execution branch gets to 1.35GW IT at YE28.
That’s another 550MW IT, or roughly 770MW gross.
IREN already has 4.4GW gross of announced CY28+ capacity.
So I only need ~17.5% of that later capacity to convert by YE28.
That’s not where the aggressive assumption is.
The real assumption is the economics:
95% monetization
× $20M ARR/IT-MW
And even that isn’t particularly heroic.
IREN is already signing recent 3-year contracts at >$20M/IT-MW, with ~2-year GPU paybacks and 45–55% customer prepays.
I’m also giving Rubin zero pricing uplift.
That may prove conservative.
WhiteFiber’s filed VR200 deal implies ~$7.14/GPU-hour versus ~$4.75 on a separate B300 deal.
Not apples-to-apples. But directionally, Rubin pricing coming in above Blackwell would hardly be surprising.
And NVIDIA is showing Rubin at up to 30x throughput/MW vs GB300 on a specific agentic workload.
I’m obviously not multiplying IREN pricing by 30x.
The point is simpler:
Customers may get dramatically more economic output from the same scarce MW while IREN’s pricing remains strong.
Dell also just exited the quarter with a $95B AI-server backlog.
So the demand backdrop isn’t exactly weakening.
Now the valuation:
1.35GW × 95% × $20M = $25.65B ARR
At 4.25x ARR:
$109B operating value
$10B remaining pipeline
− $34B net debt
= $85B equity value
÷ 520M diluted shares
= ~$163/share at YE28
Discounted back at 12%:
~$126/share today.
And I’m not pretending the growth is free.
My normal model uses ~508M shares and ~$24B net debt.
This branch uses 520M shares and $34B net debt.
At 4.0x ARR: ~$116 today
At 4.25x: ~$126
At 4.5x: ~$135
That’s what surprised me.
You can get to a very different outcome without needing the crazy stuff.
No $30M+/MW portfolio pricing.
No NVIDIA backstop.
No huge Mirantis software business.
No full pipeline conversion.
No faster build.
No major multiple rerating.
This isn’t my base case or a new price target.
It’s a high-execution branch.
But I’m paying a lot more attention to it now.
As always: I own $IREN. NFA.

Tree retweeted

$IREN: Built for a Tougher Financing Market
One of the more interesting takeaways from @danroberts0101's latest interview was his commentary around customer prepayments and how $IREN could lean on them more heavily in a tougher financing environment.
He seems as confident as ever despite the current macro / market backdrop, and I think there is a good reason for that.
$IREN is in an ideal position to push for customers to fund a larger share of the capex bill because the company is no longer pre-selling capacity years in advance.
In contrast, a company like $CRWV, with its ~$104B backlog, negotiated and signed many of those contracts months ago under the assumption that financing would remain readily available.
That led $CRWV to actually de-prioritize prepayments at the start of 2026, according to management at the time, leaving the company with a much larger capex bill that now has to be financed primarily through debt and other external capital.
For anyone paying attention, $IREN has proven this year through its contracting strategy that it is by far one of the most nimble and flexible neoclouds in the sector.
Know what you own!

IREN’s @danroberts0101 speaks to @ArjunKharpal about AI financing and demand on CNBC.
Watch the full interview.
Bought more $IREN today. Short term calls trying to catch the rebound are obviously down but the turnaround is near. You’d have to be insane to think they won’t have some big news and a 2027 ARR guidance coming up. Hang in there. It’s just markets being markets. Unfortunately the stock is easy to manipulate. Improving fundamentals will quickly rerate us.

Tree retweeted

Nvidia: We're guiding to 70% revenue growth next year. There's incredible AI demand for 100% growth, but we can't supply it.
Google: Everyone wishes they had DOUBLE the compute capacity right now. There's so much AI demand.
Bloomberg/FT: There's a $500 million market-cap Korean neocloud no one has ever heard of and it traded poorly on its IPO first day. AI IS DEAD. EVERYONE FREAK OUT AND PANIC!
Tree retweeted

"There's more customer demand than we can build for. 2026 is largely sold out, recent 3-year contracts are at more than double the prior year's pricing, and demand for 2027 covers it several times over... Conversations on 2028 capacity are already underway." — Dan
With earnings likely around Nov 5, flexing this level of pricing power sends a massive signal about where 2027 capacity rates are headed.
Furthermore, the fact that 2028 discussions are already taking place proves just how severe the power constraints really are. Bullish on $IREN.

How to be dumb 101:
Watch $IREN fall. Skip the financing math. Declare victory.
If your bear case is “capex is enormous, so shareholders face crippling dilution,” show the funding bridge.
Start with contracting.
At its latest results, IREN disclosed CY2026 capacity largely sold and significant CY2027 capacity still under negotiation.
Those future deployments can capture newer commercial terms. Higher spot prices don’t reprice old contracts, but they matter when negotiating capacity that hasn’t been sold.
IREN has been selective about customer quality, pricing, prepayments and duration. Higher equipment costs matter too. The question is what each deployment earns relative to its cost.
Recent three-year contracts exceeded $20M in annual revenue per IT MW, with estimated GPU-and-ancillary paybacks around two years after direct operating costs. That excludes campus costs, financing, overhead and taxes—but it establishes a meaningful starting point.
Now follow the money.
Microsoft: $3.6B of GPU financing at approximately 6%, excluding fees. Together with customer prepayments, approximately 96% of associated GPU capex funded.
Mackenzie: $2.4B of equipment financing at 9%, covering approximately 90% of associated GPU capex.
Recent customer prepayments: 45–55% of GPU capex.
Illustratively, where those terms apply to the same deployment:
$100 equipment cost
$90 equipment debt
$50 customer prepayment
$140 gross funding
That leaves $40 above equipment cost to help fund infrastructure, before taxes, reserves and timing restrictions.
The debt must be repaid, and the prepayment reduces later customer collections. But the equipment bill clearly isn’t the common-equity requirement.
Then consider Horizons after acceptance and stabilization.
Management reported the entire data-center portfolio, including Horizons 1–4, unencumbered at FY26 results.
A future secured Horizon financing would offer lenders completed physical infrastructure supported by contracted revenue from Microsoft, an investment-grade counterparty.
That should be a materially stronger lending proposition than an unfinished project with uncertain customers.
CoreWeave’s unsecured bond yield is not a quote for that future loan.
Even if new financing costs more than earlier deals, higher interest expense does not automatically destroy the project economics. Lenders still need adequate cash flow after existing obligations, and actual terms matter.
IREN has already demonstrated that Microsoft-backed GPU cash flows can attract investment-grade financing. Financing the stabilized data centers is the next capital-recycling opportunity, subject to execution and the existing lenders’ rights.
Now put the ATM argument in context.
The August FY27 framework was $25–30B of capex, approximately $14B of existing cash and committed funding, and another $8B of targeted GPU financing/prepayments.
If that target is achieved, $3–8B remains BEFORE data-center financing, internally generated operating cash and corporate financing.
That is not a disclosed ATM requirement. Later liquid-cooled GPU purchases also create FY28 funding needs.
And what remains when a customer contract expires?

IREN retains its owned land and buildings, grid access and installed infrastructure. A three-year customer contract doesn’t put a three-year expiry date on the campus.
Once equipment debt is repaid, commercially useful GPUs can earn another contract without another full hardware purchase. Alternatively, IREN can refresh the compute while reusing compatible infrastructure.
New GPUs remain expensive. Retaining the site beneath them is the advantage. Ownership also doesn’t mean every associated debt disappears at contract expiry.
IREN’s new liquid-cooled designs were developed with NVIDIA for successive GPU generations, evolving cooling and 800VDC. DSX MaxLPS offers a further route to more useful compute within existing power limits.
That supports infrastructure reuse and adaptability.
CoreWeave’s credit scare should make investors examine customer credit, collateral, debt service and asset ownership more carefully.
IREN still has delivery, financing and dilution risk. Mackenzie carries a parent payment guarantee. A tighter credit market can affect the next transaction.
But around $27, my bullish case is that successful execution can leave shareholders with paid-down compute, reusable infrastructure and a repeatable way to finance growth.
If you disagree, show the contract economics and residual equity requirement that break that case.
A red chart isn’t a capital model.
Tree retweeted
The whole Nscale situation is wild when you break down the facts:
Current Energized Capacity: Barely ~30–40 MW operational (their flagship Glomfjord site in Norway is actually doing only 6.4 MW today).
IPO Valuation Target: Aiming for an insane $35B valuation.
Anthropic Deal: A massive $45B backlog on paper (West Virginia), but it’s still early-stage construction and years away from delivering.
Elite Backers: Backed by heavyweights like Nvidia, Citadel, and Jane Street.
Origins: Former Aussie BTC miner (spun out of Arkon Energy).
The irony is incredible. If big money and Wall Street are willing to pour tens of billions into an unproven, paper-pipeline Aussie ex-miner, they should be backing $IREN instead. IREN already has hundreds of megawatts energized, operational FTM substations, and proven execution on the ground.
Competitor fallout = a bigger moat for $IREN.

Microsoft has pulled out of a UK data center deal with British neocloud Nscale at a critical time for the startup’s initial public offering hopes, the Telegraph reported. bloomberg.com/news/articles/…

Biggest 🤡 on X. Just commenting on short term behavioral trends like he saw jt coming. I want to see a deep dive explanation from this idiot on exactly why $IREN isn’t set up to succeed. If you can prove me wrong LOGICALLY then I will fully admit it. $IREN isn’t the best positioned neocloud for this environment. Period.
Coming Retard doesn’t understand some Neoclouds have waited to sign future capacity. All fears, costs, additionally financing stress, all get passed down to customers. Welcome to $IREN MF. No patience anymore for this bs. Do the research.
🚨 Spoiler alert 🚨
Neoclouds locked in multi year contracts way under spot and don’t get this price.
#knowwhatyouown
Tree retweeted
While neocloud investors got absolutely wrecked last week, GPU rental prices skyrocketed.
B300 rates are now up >20% over the past month.
Know what you own...
H/T: @matthew_sigel
$IREN $NBIS $CRWV


Tree retweeted
I think it’s time to call on @danroberts0101 and $IREN board and execs to buy some shares. Doesn’t need to be anything crazy but for the love of god we need a show of faith and belief in how cheap this company is. Time for action. @mikealfred let’s make it happen!
Us retail have been catching this falling knife all year. I have added almost weekly. Time to back us up.
