
Fix the money, fix the world. ₿itcoin
Planet Earth
Joined April 2022
- Tweets1.6K
- Following218
- Followers320
- Likes3.9K





Paul Connolly retweeted

@STRC_live
$MORE from @smarterwebuk was the only BTC preferred equity which had positive price action yesterday. When are you going to update your tracker.
Paul Connolly retweeted

$MORE – A GENERATION-BY-GENERATION LOOK AT INVESTING
Day 3: Generation X (Born 1965–1980, aged 46–61)
Over the past two days I've looked at Generation Z and Millennials, exploring their financial challenges, investing habits and why $MORE might appeal to them.
Today it's Generation X.
Many people in this generation have spent decades working, raising families, paying mortgages and hopefully building some financial security along the way.
But I think Generation X faces a particular challenge when it comes to retirement, and it's something that doesn't always get enough attention.
Generation X has, in many ways, fallen between two very different pension eras.
Many Baby Boomers benefited from generous final-salary pension schemes, where retirement income was largely determined by salary and years of service.
But during Generation X's working lives, many private-sector employers began closing these schemes to new employees, moving towards pensions where the individual carries much more of the investment risk.
And here's something worth remembering.
Automatic enrolment into workplace pensions didn't even begin in the UK until October 2012, with the rollout taking until 2018.
By then, many Generation X workers were already in their thirties, forties or even early fifties.
That means some missed years, potentially decades, of the automatic pension contributions that younger generations now benefit from.
Of course, many Gen X workers did have good workplace pensions, but others were left having to make their own retirement arrangements much later in their careers.
I think this is an important distinction.
For a generation now approaching retirement, there isn't necessarily another 30 or 40 years available to make up for lost pension contributions.
And that's why I think investments capable of generating income deserve serious consideration.
Which brings me to $MORE.
For anyone unfamiliar with it, $MORE is a perpetual preferred equity issued by The Smarter Web Company.
It currently carries a variable annual dividend rate of 12%, calculated against a £100 reference amount per share, with dividends scheduled weekly.
It's the possibility of reinvesting those weekly dividends that I find particularly interesting.
Rather than spending the income, you use it to purchase additional shares. Those shares potentially generate further dividends, which can themselves be reinvested.
Over time, this creates the potential for compounding.
Let's consider two very different situations.
SCENARIO 1 – INVESTING £100 A WEEK INTO A STOCKS & SHARES ISA
Imagine you're 45 or 50 years old and decide to start putting £100 a week into $MORE through your Stocks & Shares ISA.
That's £5,200 a year, well within the current £20,000 annual ISA allowance.
You reinvest every dividend and continue contributing £100 each week.
Assuming the dividend remains at 12%, the shares can always be purchased at £100 and the dividends are reinvested weekly, here's what the mathematics suggests.
AFTER 5 YEARS
Total invested: £26,000
Potential portfolio value: £35,571
Potential weekly dividend: £82
AFTER 10 YEARS
Total invested: £52,000
Potential portfolio value: £100,340
Potential weekly dividend: £232
AFTER 15 YEARS
Total invested: £78,000
Potential portfolio value: £218,275
Potential weekly dividend: £504
AFTER 20 YEARS
Total invested: £104,000
Potential portfolio value: £433,019
Potential weekly dividend: £999
Think about that final example.
Someone investing £100 a week over 20 years would have contributed £104,000 of their own money.
Under these assumptions, reinvested dividends could have helped build a portfolio worth approximately £433,000, potentially generating almost £1,000 every week if they stopped reinvesting.
And because the investment would be held within a qualifying Stocks & Shares ISA, that dividend income could be withdrawn free of UK income tax under current rules.
For somebody approaching retirement, that's a potentially substantial additional income stream.
But let's consider another situation that I suspect many people in Generation X will recognise.
SCENARIO 2 – WHAT IF YOU INHERITED £100,000 TODAY?
Perhaps you've inherited money from a parent or relative.
You've received £100,000 and don't immediately need it for living expenses.
What if you invested that money into $MORE and reinvested every dividend until retirement?
Using exactly the same assumptions as before, here's how the figures develop.
AFTER 5 YEARS
Original investment: £100,000
Potential portfolio value: £182,086
Potential weekly dividend: £420
AFTER 10 YEARS
Original investment: £100,000
Potential portfolio value: £331,553
Potential weekly dividend: £765
AFTER 15 YEARS
Original investment: £100,000
Potential portfolio value: £603,712
Potential weekly dividend: £1,393
AFTER 20 YEARS
Original investment: £100,000
Potential portfolio value: £1,099,274
Potential weekly dividend: £2,537
That final number is particularly striking.
In this hypothetical scenario, £100,000 invested today could become approximately £1.1 million over 20 years.
And if the 12% dividend rate were still being paid at retirement, that portfolio could potentially generate over £131,900 a year in dividends, before any applicable taxes.
It's important to understand that these are mathematical projections, not expected or guaranteed returns.
They assume two decades of uninterrupted dividends at 12%, a constant £100 share price, immediate reinvestment, no fees and no losses. All of those assumptions could prove unrealistic.
There's also an important ISA distinction.
You couldn't simply put the entire £100,000 inheritance into your own ISA in one tax year. The current annual allowance is £20,000, so you would need to move money into an ISA over multiple tax years, subject to future allowances.
Investing the full £100,000 immediately outside an ISA could result in dividend taxes that materially reduce the figures above.
Nevertheless, I think both examples demonstrate why dividend reinvestment deserves attention.
And there's another important factor for Generation X: inflation.
People approaching retirement need to think about what their money will actually buy in 10 or 20 years.
Simply maintaining the same amount of money isn't necessarily enough if everyday living costs continue rising.
An income-producing investment that allows dividends to be reinvested could potentially help build a larger portfolio before retirement.
Of course, $MORE isn't inflation-linked, and a 12% dividend today doesn't guarantee the same rate in the future.
What about the risks?
$MORE is an equity investment, not a bank deposit.
The dividend rate is variable, payments can be suspended, the share price can decline and the company has redemption rights. Its Bitcoin treasury strategy also introduces financial risks. Concentrating a substantial amount of retirement savings in one issuer would increase those risks considerably.
The weekly dividend entitlement is based on the £100 reference amount per share, not necessarily the price paid in the market.
But I believe $MORE gives investors something genuinely interesting to research: a preferred equity designed around regular cash distributions, with the potential to reinvest those distributions while building towards retirement.
And that brings me back to Generation X.
Some people will be able to invest £100 a week. Others might receive an inheritance, sell a property or release capital from a business.
The amounts and circumstances will be different, but the question is similar.
How could the money available today be put to work to create an income later in life?
For those who understand the structure and accept the risks, I think $MORE deserves consideration in that conversation.
Particularly for a generation where many didn't benefit from decades of automatic pension saving or the final-salary retirement arrangements enjoyed by some of their predecessors.
Because reaching retirement with investments capable of generating regular income could provide something particularly valuable.
More financial freedom and more choice over how you spend your time.
Tomorrow: Baby Boomers.
For many, retirement has already arrived, so I'll be looking at $MORE from a different perspective: generating weekly income from capital already accumulated, without needing to wait another 10 or 20 years.
$MORE $SWC #GenerationX #Investing #ISA #Dividends #Retirement

$MORE – A GENERATION-BY-GENERATION LOOK AT INVESTING
Day 2: Generation Y – Millennials (Born 1981–1996, aged 30–45)
Yesterday I looked at Generation Z and how time can be their biggest advantage when investing.
Today I'm looking at Millennials, and I actually think this is one of the most interesting generations when considering an investment such as $MORE.
Why? Because Millennials are at a stage of life where their financial priorities are changing.
Many are now established in their careers, earning more than they did in their twenties, but they're also dealing with mortgages, childcare, rising household expenses and the growing realisation that retirement might not be as financially comfortable as they once imagined.
They're earning money, but a surprising amount of it is already spoken for.
And I think this is where investing for income starts becoming particularly interesting.
Research from interactive investor's 2026 Great British Retirement Survey found that Millennials have a typical pension pot of approximately £25,000, despite expecting to retire with around £450,000.
That's quite a gap to bridge, even allowing for another 20 or 30 years of working.
What's interesting is that Millennials are already investing outside their pensions. The same research suggests they're investing around £400 a month on average outside pension arrangements.
So the appetite to invest is clearly there.
But I wonder how many have seriously considered building an additional source of income rather than focusing entirely on capital appreciation?
This is why I believe $MORE deserves their attention.
$MORE is a perpetual preferred equity issued by The Smarter Web Company, currently carrying a 12% annual dividend rate, calculated against a £100 reference amount per share, with dividends scheduled weekly.
It's a different proposition from buying ordinary shares in the hope that the price appreciates.
With $MORE, the primary attraction is the potential income.
Let's look at the numbers.
At the current dividend rate:
100 shares = £1,200 annually.
250 shares = £3,000 annually.
500 shares = £6,000 annually.
That's approximately £23, £58 and £115 a week respectively, before tax.
These figures assume the current dividend rate continues and the shares are held for a full year. The actual investment cost depends on the market price, and the dividend rate can change.
Now imagine being 35 or 40 years old and beginning to build an investment portfolio that generates an additional income stream.
You don't necessarily need that income today.
Perhaps you reinvest it, buying additional shares and potentially increasing the dividends received in the future.
Perhaps you use part of it to help with household expenses while reinvesting the remainder.
Or perhaps you simply want to build investments that could eventually supplement your earnings and give you greater financial flexibility.
For Millennials, I think flexibility is enormously valuable.
There's another reason I believe income-producing investments deserve consideration: inflation.
Millennials have experienced some significant financial shocks during their adult lives, including the 2008 financial crisis, the pandemic and the subsequent surge in inflation and interest rates.
They understand what happens when household expenditure increases faster than wages.
An additional investment income stream could help offset some of those rising costs, although $MORE isn't inflation-linked and its dividend isn't guaranteed to maintain purchasing power.
I also think there's an interesting psychological difference between owning an investment purely for price appreciation and owning one that aims to distribute income regularly.
With a growth share, you might spend years waiting for the market to recognise its value.
With an income-focused preferred share, you're investing primarily for distributions rather than relying entirely on a higher future selling price.
That doesn't make it risk-free. $MORE is an equity investment, not a savings account. Dividends can be suspended, its rate can change, its market value can fall, and The Smarter Web Company's Bitcoin treasury strategy introduces additional risks. The preferred shares do, however, rank ahead of ordinary shareholders and carry cumulative dividend rights.
What excites me about $MORE is the opportunity to make the money you've already earned start working for you, potentially generating income every single week, and then having the choice of spending that income or reinvesting it to build something substantially bigger over the years ahead.
I think Millennials are reaching the age where building wealth becomes just as much about generating income as accumulating assets.
And with another 20 to 30 years potentially ahead before retirement, the ability to reinvest that income could be particularly valuable.
That's why I believe $MORE could appeal to this generation.
Not because they're looking to get rich overnight, but because many are now thinking seriously about making the money they've already earned work harder for them.
Tomorrow: Generation X.
A generation approaching retirement, where protecting wealth, generating income and reducing dependence on employment become increasingly important.
$MORE $SWC #Millennials #Investing #Dividends


Paul Connolly retweeted

@Trading212
I would like Trading212 to please list the following:
Instrument Ticker = MORE
ISIN = GBOOCOHJOD12
Listing Exchange = London Stock Exchange
Platform = Invest and Stocks & Shares ISA
Currency = GBP
Instrument type = Stock


Paul Connolly retweeted
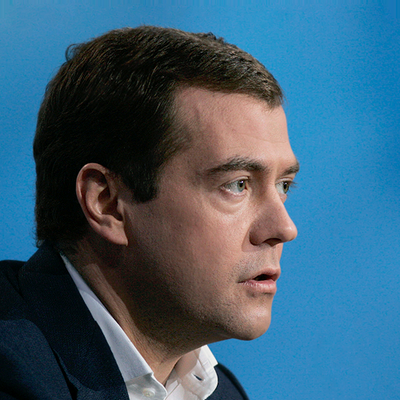
“My biggest concern at the moment is not our economy, is not the European Union, is not America, is not Chinа. My biggest concern is the impact of Russia on our society," said Merz, the grandson of a Nazi.
Great chancellor! How lucky you Germans are 😂
Paul Connolly retweeted

The next bull run hasn’t truly started yet.
When $STRC hits $100 par the games will begin.
#MORE is building very nicely. It will continue to need some more time but hitting £100 par is simply a matter of when, not if.
There were 2 stellar performances from @asjwebley and @millercole on @TimKotzman’s inaugural Digital Credit Digital Conference and it’ll be great to welcome Tim back to the UK in November! 🙌
If you haven’t watched the full event yet I highly recommend it. Bvid link in the comments below 👇
Momentum is building but we’re still only just getting started.
Onwards! 🚀

#MORE is continuing to build liquidity.
Just 5 days of trading in and building nicely.
JP Morgan expects Bitcoin to be the best performing asset in the next decade.
Saylor is now talking publicly about Strategy being the central bank for of the crypto economy.
The direction of travel is clear.
$SWC is positioned perfectly.
Onwards! 🚀
Paul Connolly retweeted

I've come to this conclusion too.
Fiat and fiat tax is slavery. Most people won't even acknowledge this no matter how many times you explain it to them.
Banks create money out of thin air. Governments create billions in taxpayer debt every day to spend however they like.


Paul Connolly retweeted
Watch: French undercover cops fuelling the current African uprising - Globalist controlled all the way...nothing to do with school #FrenchProtests
Paul Connolly retweeted

I have a small LTD company.
Had a chat with my business partner yesterday.
Portion of our tax saving will be allocated to MORE. Hopefully next month.
🫱🏻🫲🏼
Paul Connolly retweeted

Does your Business need $MORE?
"Under Part 9A of the Corporation Tax Act 2009, most qualifying dividends received by UK limited companies are exempt from corporation tax"
Could $MORE become a serious alternative for UK businesses holding large amounts of surplus cash in their bank accounts?
I've been thinking about this quite a bit, and I don't think the potential corporate market for MORE is getting nearly enough attention.
There are thousands of profitable UK businesses holding anything from £100,000 to several million pounds in cash reserves.
Some of that money is needed for running the business, paying staff, VAT, corporation tax and other commitments. That money obviously needs to remain accessible and secure.
But what about the surplus cash that businesses have no immediate plans to spend?
Money that might sit in a business savings account for years, earning interest which is then subject to corporation tax.
This is where I think $MORE becomes particularly interesting.
Let's look at a business holding £500,000 in surplus cash.
Imagine that business earns 3% interest annually from its bank. That's an illustrative rate rather than a specific bank offer.
£500,000 at 3% generates £15,000 in interest each year.
For a company paying corporation tax at the 25% main rate, that £15,000 becomes £11,250 after tax.
The business has earned an effective 2.25% return on its money.
Now compare that with MORE, the new sterling-denominated preferred share issued by The Smarter Web Company and listed on the London Stock Exchange.
MORE launched with an initial annual dividend rate of 12%, calculated against a £100 reference amount per preferred share, with dividends scheduled to be paid weekly.
For illustration, assume that same business could purchase 5,000 MORE shares at £100 each, investing £500,000.
At the initial dividend rate, those shares would generate:
£60,000 annually.
Approximately £1,150 per week.
But there's something potentially even more interesting than the dividend itself.
The corporation tax treatment.
Under Part 9A of the Corporation Tax Act 2009, most qualifying dividends received by UK limited companies are exempt from corporation tax.
And this isn't simply an assumption I've made about MORE.
Page 125 of MORE's own FCA-approved prospectus specifically addresses corporate shareholders, stating that those subject to UK corporation tax should generally be able to claim an exemption on dividends received, subject to the relevant anti-avoidance provisions.
That is an important distinction.
The interest earned in a business bank account is normally included in the company's taxable profits.
Qualifying dividend income received from MORE would generally not be.
So, using our £500,000 example:
Bank account at 3%:
£15,000 gross annual interest.
£3,750 corporation tax at 25%.
£11,250 retained by the company.
MORE, purchased at £100 per share, with its initial 12% dividend maintained:
£60,000 annual dividend income.
Generally exempt from corporation tax if the relevant conditions are satisfied.
Potentially £60,000 retained within the company.
That's a difference of £48,750 a year on the same £500,000 of capital.
And here's another way of looking at it.
For a business paying 25% corporation tax, a bank savings account would need to pay 16% gross interest for the company to retain the equivalent of a 12% tax-exempt dividend yield.
Sixteen per cent.
Of course, that doesn't make MORE equivalent to a bank account, and that distinction matters enormously.
MORE is an investment in a perpetual preferred share, not a deposit. Its market price can fall, its initial dividend rate can change, payments can be deferred and the capital isn't protected in the way eligible bank deposits are.
You are accepting substantially more risk in exchange for the possibility of a substantially higher return.
But I think it's worth understanding what MORE actually offers.
It's a UK-listed security.
It's denominated in sterling, so UK businesses don't need to exchange pounds into dollars to invest.
It offers scheduled weekly dividends rather than waiting for monthly, quarterly or annual interest payments.
The dividends are cumulative, meaning unpaid amounts accumulate, although that doesn't guarantee when or whether they will ultimately be paid.
And behind MORE is The Smarter Web Company, with its Bitcoin treasury, operating businesses and capital-raising strategy.
That's a very different proposition from leaving money in the bank, but also a very different risk profile. Bitcoin doesn't generate income itself, and the issuer needs sufficient cash and distributable profits to sustain the dividends.
The point isn't that businesses should empty their bank accounts and buy MORE.
That would be ridiculous.
Companies need liquidity, security and certainty for their day-to-day obligations. Those funds belong in suitable bank accounts or other appropriate cash-management products.
The question is what companies should consider doing with genuinely surplus capital that isn't needed for years.
Could a business sensibly allocate a modest percentage of its longer-term surplus reserves to an income investment like MORE?
Could the weekly dividends provide additional cash flow for the business?
Could those receipts then be reinvested, used to fund expansion, purchase assets or simply accumulate within the company?
And could the potentially favourable corporation tax treatment make MORE particularly attractive to UK corporate investors compared with conventional taxable savings income?
I think these are questions worth asking.
There's another important distinction, too.
The tax treatment we're discussing applies to qualifying dividends received within the company. It doesn't mean profits from selling the shares are tax-free, or that directors can withdraw the dividends personally without tax consequences. A substantial investment portfolio can also affect certain reliefs available to trading businesses, so professional tax advice matters.
But the underlying opportunity is still fascinating.
MORE only began trading on 14 October. It's very early days, and the product needs to establish a track record, build trading liquidity and demonstrate that its dividend policy is sustainable.
Nevertheless, I think people may be underestimating the market that could eventually develop around it.
We talk about individuals wanting weekly income.
We talk about pension funds, income investors and institutions.
But what about the enormous amount of surplus capital held inside UK limited companies?
Company directors already understand the difference between earning interest before corporation tax and receiving qualifying dividend income that may be exempt.
If MORE can prove itself over time, I can see why that market might start paying attention.
For me, this is one of the most interesting potential sources of demand for $MORE that hasn't been explored nearly enough.
And I'd be interested to know how many business owners have actually considered it.
#UKDividends #DividendInvesting #PassiveIncome
#FTSE


Paul Connolly retweeted

Food for thought for any businesses with surplus cash reserves 💪🏻😎🧐
Could $MORE become a serious alternative for UK businesses holding large amounts of surplus cash in their bank accounts?
I've been thinking about this quite a bit, and I don't think the potential corporate market for MORE is getting nearly enough attention.
There are thousands of profitable UK businesses holding anything from £100,000 to several million pounds in cash reserves.
Some of that money is needed for running the business, paying staff, VAT, corporation tax and other commitments. That money obviously needs to remain accessible and secure.
But what about the surplus cash that businesses have no immediate plans to spend?
Money that might sit in a business savings account for years, earning interest which is then subject to corporation tax.
This is where I think $MORE becomes particularly interesting.
Let's look at a business holding £500,000 in surplus cash.
Imagine that business earns 3% interest annually from its bank. That's an illustrative rate rather than a specific bank offer.
£500,000 at 3% generates £15,000 in interest each year.
For a company paying corporation tax at the 25% main rate, that £15,000 becomes £11,250 after tax.
The business has earned an effective 2.25% return on its money.
Now compare that with MORE, the new sterling-denominated preferred share issued by The Smarter Web Company and listed on the London Stock Exchange.
MORE launched with an initial annual dividend rate of 12%, calculated against a £100 reference amount per preferred share, with dividends scheduled to be paid weekly.
For illustration, assume that same business could purchase 5,000 MORE shares at £100 each, investing £500,000.
At the initial dividend rate, those shares would generate:
£60,000 annually.
Approximately £1,150 per week.
But there's something potentially even more interesting than the dividend itself.
The corporation tax treatment.
Under Part 9A of the Corporation Tax Act 2009, most qualifying dividends received by UK limited companies are exempt from corporation tax.
And this isn't simply an assumption I've made about MORE.
Page 125 of MORE's own FCA-approved prospectus specifically addresses corporate shareholders, stating that those subject to UK corporation tax should generally be able to claim an exemption on dividends received, subject to the relevant anti-avoidance provisions.
That is an important distinction.
The interest earned in a business bank account is normally included in the company's taxable profits.
Qualifying dividend income received from MORE would generally not be.
So, using our £500,000 example:
Bank account at 3%:
£15,000 gross annual interest.
£3,750 corporation tax at 25%.
£11,250 retained by the company.
MORE, purchased at £100 per share, with its initial 12% dividend maintained:
£60,000 annual dividend income.
Generally exempt from corporation tax if the relevant conditions are satisfied.
Potentially £60,000 retained within the company.
That's a difference of £48,750 a year on the same £500,000 of capital.
And here's another way of looking at it.
For a business paying 25% corporation tax, a bank savings account would need to pay 16% gross interest for the company to retain the equivalent of a 12% tax-exempt dividend yield.
Sixteen per cent.
Of course, that doesn't make MORE equivalent to a bank account, and that distinction matters enormously.
MORE is an investment in a perpetual preferred share, not a deposit. Its market price can fall, its initial dividend rate can change, payments can be deferred and the capital isn't protected in the way eligible bank deposits are.
You are accepting substantially more risk in exchange for the possibility of a substantially higher return.
But I think it's worth understanding what MORE actually offers.
It's a UK-listed security.
It's denominated in sterling, so UK businesses don't need to exchange pounds into dollars to invest.
It offers scheduled weekly dividends rather than waiting for monthly, quarterly or annual interest payments.
The dividends are cumulative, meaning unpaid amounts accumulate, although that doesn't guarantee when or whether they will ultimately be paid.
And behind MORE is The Smarter Web Company, with its Bitcoin treasury, operating businesses and capital-raising strategy.
That's a very different proposition from leaving money in the bank, but also a very different risk profile. Bitcoin doesn't generate income itself, and the issuer needs sufficient cash and distributable profits to sustain the dividends.
The point isn't that businesses should empty their bank accounts and buy MORE.
That would be ridiculous.
Companies need liquidity, security and certainty for their day-to-day obligations. Those funds belong in suitable bank accounts or other appropriate cash-management products.
The question is what companies should consider doing with genuinely surplus capital that isn't needed for years.
Could a business sensibly allocate a modest percentage of its longer-term surplus reserves to an income investment like MORE?
Could the weekly dividends provide additional cash flow for the business?
Could those receipts then be reinvested, used to fund expansion, purchase assets or simply accumulate within the company?
And could the potentially favourable corporation tax treatment make MORE particularly attractive to UK corporate investors compared with conventional taxable savings income?
I think these are questions worth asking.
There's another important distinction, too.
The tax treatment we're discussing applies to qualifying dividends received within the company. It doesn't mean profits from selling the shares are tax-free, or that directors can withdraw the dividends personally without tax consequences. A substantial investment portfolio can also affect certain reliefs available to trading businesses, so professional tax advice matters.
But the underlying opportunity is still fascinating.
MORE only began trading on 14 October. It's very early days, and the product needs to establish a track record, build trading liquidity and demonstrate that its dividend policy is sustainable.
Nevertheless, I think people may be underestimating the market that could eventually develop around it.
We talk about individuals wanting weekly income.
We talk about pension funds, income investors and institutions.
But what about the enormous amount of surplus capital held inside UK limited companies?
Company directors already understand the difference between earning interest before corporation tax and receiving qualifying dividend income that may be exempt.
If MORE can prove itself over time, I can see why that market might start paying attention.
For me, this is one of the most interesting potential sources of demand for $MORE that hasn't been explored nearly enough.
And I'd be interested to know how many business owners have actually considered it.
#UKDividends #DividendInvesting #PassiveIncome
#FTSE
Paul Connolly retweeted

Business owners should read this 👀
Earn $MORE.
Paul Connolly retweeted

JPMORGAN CEO JAMIE DIMON ONCE SAID "IN 10 YEARS, #BITCOIN WILL BE CLOSED DOWN"
TODAY, HIS OWN BANK SAID BTC WILL THE BEST PERFORMING ASSET OVER THE NEXT DECADE 🤡


Paul Connolly retweeted

A farmer, tired of rats destroying his crops and stealing his grain, came up with a clever but cruel plan. He threw a dead pig into a deep, abandoned well. Attracted by the smell, nearly 80 rats rushed into the well to feast on the carcass. At first, everything seemed wonderful. There was more than enough food for everyone, and the rats ate until they were satisfied.
But when the food was gone, they discovered something terrifying. The walls of the well were too steep to climb. They were trapped. Days passed, and hunger turned into desperation. Desperation turned into aggression. The rats that had once eaten peacefully beside one another began fighting for survival. Eventually, they began killing and eating each other.
One by one, their numbers dwindled until only a single rat remained. Its eyes were bloodshot, and it had survived by consuming its own kind. Then the farmer returned, lowered a rope into the well, and rescued the last surviving rat. But he didn't save it out of kindness or compassion.
The farmer knew the rat had learned to survive by hunting other rats. When he released it into his fields, it would continue killing its own kind instead of eating his grain. The farmer had turned his enemy into his greatest weapon.
And that is the lesson of divide and conquer. Those who control the trap don't need to fight the battles themselves. They simply create the conditions in which others turn against one another.
The rats believed their enemies were the other rats. They never realized that the true enemy was the farmer who had put them there.
The greatest danger isn't always the enemy standing in front of you. Sometimes it's the one who created the conflict and stands quietly watching you destroy each other.
Before you turn against your neighbor because of their political beliefs, ask yourself who benefits from keeping Americans divided. While we fight each other over Republican and Democrat, we may be overlooking those who profit from the conflict. Perhaps the real question isn't which side you're on, but who built the well—and why they want us fighting at the bottom of it.
