




Faisal Afzal retweeted

مریم نوازشریف کا دھی رانی پروگرام مستحق خاندانوں کی خوشیوں میں شریک ہونےکی بہترین مثال ہے۔لاہور میں150 جوڑوں کی اجتماعی شادیاں،ہر جوڑے کو 2لاکھ روپےسلامی اور21 اقلیتی جوڑوں کی شرکت قابلِ تحسین ہے۔2سال میں8 ہزار جوڑوں کی شادیاں اس منصوبے کی کامیابی کا ثبوت ہیں۔
@MaryamNSharif
Faisal Afzal retweeted
اثاثوں میں تقریباً 4 کروڑ 32 لاکھ روپے کا اضافہ کیسے ہوا؟
2026 میں ظاہر کردہ مجموعی اثاثے 9 کروڑ 70 لاکھ روپے، جبکہ صرف کیش 3 کروڑ 25 لاکھ روپے سے زائد ظاہر کیا گیا، اتنی بڑی نقد رقم کہاں سے آئی اور کہاں رکھی گئی؟
Faisal Afzal retweeted
#فضلو_اختجاج_ٹھس
#خاندانی_چور_فضلو
ٹاپ بریکنگ
فضل الرحمان کے بھائی لطف الرحمان کے بھی اثاثوں اور ویلتھ اسٹیٹمینٹ میں بڑے مبہم اور مشکوک تضادات منظر عام پر*
لُطف الرحمٰن کی ویلتھ اسٹیٹمنٹ میں 2021 سے2026 کےدوران اثاثے 5 کروڑ 38 لاکھ روپے سے بڑھ کر9 کروڑ 70لاکھ روپے تک پہنچ گئے،
Faisal Afzal retweeted
باپ کے بیٹے کی خوشی میں، میں کتنی خوش تھی،مگر کبھی نہیں سوچا تھا کہ زندگی مجھے یہ دن بھی دکھائے گی۔
اللہ جانے زندگی نے مزید مہلت دی تو یہ سب کیسے برداشت کروں گی۔ آپ شاید آج خوش ہیں، مگر میرے دل پر کیا گزر رہی ہے، اسکا اندازہ نہیں لگا سکتے
Faisal Afzal retweeted
#فضلو_اختجاج_ٹھس
#خاندانی_چور_فضلو
*بی ایل اے کے ایک کارندے کی والدہ کا بیان* :
"اسے مجھ سے زیادہ ڈیوٹی عزیز ہو گئی ہے، مگر کوئی میری حالت بھی تو سمجھے۔ میں فالج کی مریضہ ہوں۔ نہ وہ میرا بیٹا ہے اور نہ میرے شوہر کا بیٹا۔ میں نہیں چاہتی کہ وہ میرے گھر آئے۔
Faisal Afzal retweeted
اس نے کہا کہ والدین نے غربت اور مشکلات کے باوجود اسے اس امید پر پالا پوسا کہ وہ مستقبل میں ان کا سہارا بنے گا، مگر اس نے غلط راستہ اختیار کرکے ان کی قربانیوں کو نظرانداز کیا۔
اس نے مزید کہا کہ مذکورہ شخص اب ان کے گھر اور خاندان کا حصہ نہیں اور وہ اسے اپنا بھائی تسلیم نہیں کرتی۔
Faisal Afzal retweeted
#فضلو_اختجاج_ٹھس
#خاندانی_چور_فضلو
بی ایل اے سے منسلک ایک کارندے کی بہن سے گفتگو کا خلاصہ:
گفتگو کے دوران بہن نے اپنے بھائی سے لاتعلقی کا اظہار کرتے ہوئے واضح کیا کہ اس کے اقدامات نے نہ صرف خاندان بلکہ والدین کی زندگیوں کو بھی شدید دکھ اور اذیت سے دوچار کیا ہے۔
Faisal Afzal retweeted
اس کا کہنا تھا کہ چڑھتے سورج کو سلام کرنا اور سیاسی فائدے کے لیے مؤقف بدلنا فضل الرحمان کی سیاست کا وطیرہ بن چکا ہے۔
Faisal Afzal retweeted
#فضلو_اختجاج_ٹھس
#خاندانی_چور_فضلو
🚨*کوئٹہ سے پختون شہری نے فضل الرحمٰن کی سیاست کو دوغلا قرار دے دیا*
⭕ پختون شہری نے فضل الرحمٰن کو دوغلی سیاست کا علمبردار قرار دیتے ہوئے کہا کہ ان کی سیاست اصولوں کے بجائے ذاتی مفادات اور اقتدار کے گرد گھومتی ہے۔
Faisal Afzal retweeted
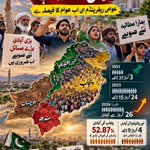
اب ناگزیر ہو چکا ہے۔
*اختیارات کی نچلی سطح تک منتقلی نا صرف وسائل کی منصفانہ تقسیم اور معاشی خود کفالت کو یقینی بنائے گی بلکہ مقامی سطح پر مخلص قیادت کو ابھار کر ملک کو حقیقی استحکام اور پائیدار ترقی کی راہ پر گامزن کرے گی۔*
Faisal Afzal retweeted
#فضلو_اختجاج_ٹھس
#خاندانی_چور_فضلو
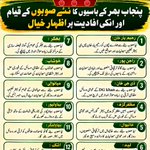
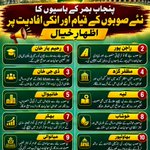
*نئے انتظامی صوبے: عام شہری کی خوشحالی اور مضبوط پاکستان کی ضمانت!*
بڑھتی ہوئی آبادی کے مسائل حل کرنے، دور دراز علاقوں کی محرومیوں کے ازالے اور عام شہری کو اس کی دہلیز پر فوری انصاف و بنیادی سہولیات فراہم کرنےکےلیے نئے انتظامی صوبوں کا قیام

Faisal Afzal retweeted
#فضلو_اختجاج_ٹھس
#خاندانی_چور_فضلو
پی ٹی آئی کے سیاست دانوں کی جانب سے خیبرپختونخوا کے عوام کے ساتھ دھوکہ، صوبے کی معدنیات کی لوٹ مار میں ملوث ہونے کا انکشاف، حاصل ہونے والی رقم سے خوارج اور افغان طالبان کی سہولت کاری کا بھی انکشاف*
آئیے دیکھتے ہیں اس ویڈیو میں
Faisal Afzal retweeted
#فضلو_اختجاج_ٹھس
#خاندانی_چور_فضلو
معدنیات پر شور مچانے والے خود گولڈ مائننگ اور معدنیات چوری میں ملوث
خیبر پختونخوا میں اپنی حکومتی نااہلی اور گورننس کی ناکامیوں پر پردہ ڈالنے کے لیے پی ٹی آئی کا گورنر راج کے خلاف گمراہ کن پروپیگنڈا*
Faisal Afzal retweeted
فضل ڈیزل دوسروں کو کرپشن کےطعنے دینےوالےپہلےاپنےخاندان کےدامن پر لگے داغ صاف کرو۔گلی83کےمبینہ بےنامی بنگلے، اسدمحمود کےٹھیکے،15سوال ضیاء الرحمٰن کی دولت نےتمہاری احتسابی سیاست کا بھانڈا پھوڑ دیاہے۔دوسروں پر انگلی اٹھانےسے پہلےاپنےگھر کا حساب دو،
#فضلو_اختجاج_ٹھس
#خاندانی_چور_فضلو
Faisal Afzal retweeted
پنجاب کی ترقی اور تعلیمی سہولیات کا اعتراف اب دوسرے صوبوں کے نوجوان بھی کر رہے ہیں۔اسی لیے خیبرپختونخوا کا طالب علم بھی پنجاب میں تعلیم حاصل کرنے کو ترجیح دےرہا ہے۔ 13 سالہ کے پی کےصوبائی کارکردگی کا یہ ایک بڑا سوال ہے۔ترقی نعروں سےنہیں،عملی کام اور عوامی سہولیات سے ثابت ہوتی ہے۔
Faisal Afzal retweeted
HUM Network’s financial dealings raise serious concerns over overseas losses, billions in transactions, family-linked payments and @Duraidqureshi1 Rs361 million salary. SECP, PSX and NAB must investigate and ensure transparency and accountability. No one is above the law!

🚨🚨Top breaking Investigative Dossier from UK exposes massive black money scandals of Duraid Qureshi & his money laundering empire run under cover of Hum Awards
An examination of official financial statements filed by HUM Network, records available through the Pakistan Stock Exchange, and corporate filings with the UK Companies House has raised serious questions about the financial practices of HUM Network and its CEO, Duraid Qureshi. The documents reveal a troubling pattern involving the valuation of overseas subsidiaries, undisclosed international event revenues, substantial inter-company balances, related-party payments, executive remuneration and tax adjustments. Taken together, these discrepancies raise fundamental questions about corporate governance, financial transparency and the treatment of public shareholders in a company listed on the Pakistan Stock Exchange.
It is worth noting that Duraid Qureshi has successfully maintained a visible presence in influential institutional circles, including frequent visits to the Ministry of Information and Broadcasting (MoIB) and ISPR. Such engagement has helped him maintain a cordial public and institutional profile.
However, the financial practices reflected in the company’s filings raise serious questions that cannot be answered through personal relationships, public appearances or a carefully cultivated corporate image. The issue is whether the management of a publicly listed company has been operating in the best interests of its shareholders or using complicated domestic and overseas corporate arrangements in ways that require closer regulatory scrutiny.
In September 2024, HUM Network organised an award show at London’s Wembley Arena. Subsequently, the company reduced the reported value of its 100% shareholding in its UK subsidiary, HUM Network UK, from PKR 95.9 million to zero, effectively recognising the entire investment as a loss in its Pakistani accounts while retaining full ownership of the subsidiary. What makes this write-down particularly questionable is that HUM Network’s UK sales increased by 22% during the same year, reaching PKR 334.3 million. How could the value of a wholly owned subsidiary be reduced to zero in the very year that business generated from the UK was growing substantially? Was this a genuine commercial loss, or does the accounting treatment warrant investigation?
The UK company’s accounts filed by Duraid Qureshi in March 2026 reveal further financial inconsistencies. Its bank cash balance had nearly doubled to £377,000, while outstanding liabilities exceeded £3.2 million and accumulated losses reached £1.958 million. More importantly, the company’s public filings did not include a Profit and Loss Account. By relying on the reporting exemptions available to small companies under UK law, the subsidiary was not required to publish detailed income and expenditure figures and also obtained exemption from statutory audit. Consequently, the actual financial performance of the Wembley event, including ticket-sale proceeds, sponsorship income, operational expenses and ultimate profitability, cannot be independently established from the publicly available accounts.
The financial treatment of inter-company transactions raises equally serious questions. After writing down the value of its UK subsidiary to zero, HUM Network’s Pakistani parent company also wrote off PKR 105.3 million owed by the same subsidiary, treating the outstanding trade receivable as irrecoverable. At the same time, the amount recorded as receivable from HUM Network’s Dubai-based subsidiary, HUM Network FZ LLC, increased from PKR 2.59 billion in 2024 to more than PKR 5.32 billion in 2026. This extraordinary increase warrants a detailed explanation regarding the nature of these transactions, the commercial purpose of the advances, the recovery arrangements and the ultimate location and utilisation of these funds. For a publicly listed Pakistani company, billions of rupees tied up in overseas subsidiaries cannot simply be treated as an internal accounting matter.
The Wembley award show itself raises fundamental questions about revenue disclosure and financial transparency. Despite the event involving thousands of tickets, no corresponding breakdown of ticket-sale proceeds has been established through the publicly available records examined. The only specific entry identified in Brent Council’s official records relates to 10 complimentary tickets, valued at £450, provided to local councillor Ajmal Akram. This does not account for the wider ticketing operation or the event’s overall financial performance. Equally concerning are the accounts of Alliance Advertising, the UK agency responsible for sponsorship arrangements for the event. Its public filings did not disclose a Profit and Loss Account and showed £1.5 million in outstanding receivables at year-end, despite reporting a zero bank cash balance. These figures raise questions about the actual collection, transfer and accounting of sponsorship revenues. There is also no identifiable accounting entry, amount or receipt in the company’s annual report to substantiate the commitment associated with the 2022 Canada Awards Show to contribute ticket proceeds towards relief for Pakistan’s flood victims. Where did the promised contribution go, and what documentary evidence exists to establish that it was actually made?
The domestic financial picture is equally revealing. During FY2025, HUM Network reported production expenses of PKR 7.68 billion and made payments amounting to PKR 2.47 billion to affiliated family-owned production entities, including MD Productions and Momina & Duraid Films, within a single financial year. These substantial related-party transactions raise questions about the commercial basis of the payments, the pricing of production services, the selection of vendors and the safeguards in place to protect ordinary shareholders. In other words, while the company reports substantial production costs and accounting losses, billions of rupees are being paid to entities affiliated with its own management and family business interests. These transactions deserve independent examination to establish whether they were conducted at arm’s length and in the genuine commercial interests of HUM Network.
Perhaps the most striking contrast is Duraid Qureshi’s own remuneration. During FY2025, he received PKR 361.2 million in salary, bonuses and other benefits as CEO. This amounts to more than PKR 36 crore annually, or approximately PKR 3 crore per month when averaged across the year. While the company’s overseas investments and operations are being presented through substantial write-downs and accumulated losses, its chief executive continues to receive exceptionally high personal remuneration. The obvious question is why public shareholders should bear the financial consequences of questionable overseas investments and reported losses while the CEO continues to receive such substantial financial rewards. The distinction between corporate losses and executive earnings is particularly important: shareholders’ capital is exposed to the company’s financial risks, whereas executive remuneration may continue to be paid regardless of the performance of individual overseas ventures.
Despite these substantial expenses and executive payouts, HUM Network’s parent company reported a net tax credit of PKR 25.2 million rather than an income tax liability, following accounting losses and adjustments. This raises further questions about the basis of the tax credit, the nature of the adjustments and whether the reported losses accurately reflect the underlying commercial performance of the business.
The central issue is therefore not simply whether HUM Network has incurred losses. It is whether those losses, overseas financial arrangements, related-party payments and executive benefits have been properly accounted for and transparently disclosed to the company’s public shareholders. Why was the UK subsidiary valued at zero despite rising UK sales? Why was a substantial receivable from that subsidiary written off? Why have the amounts recorded against the Dubai subsidiary more than doubled? Where are the detailed revenue and expenditure accounts for the Wembley show? What happened to the ticketing and sponsorship proceeds? What documentary evidence supports the promised contribution to Pakistan’s flood victims? And what independent safeguards ensure that billions of rupees paid to family-affiliated production companies represent genuine, fairly priced commercial transactions?
There is also a fundamental question of accountability: how can a CEO of a publicly listed company justify receiving more than PKR 36 crore annually in remuneration while shareholders are left to absorb the consequences of reported losses, overseas write-downs and questionable financial arrangements?
These are serious questions arising from corporate filings and financial disclosures, not conclusions that should be prejudged without a full investigation. The Pakistan Stock Exchange, Securities and Exchange Commission of Pakistan, Federal Board of Revenue, National Accountability Bureau (NAB) and other relevant regulatory authorities should examine the transactions, obtain supporting bank records, scrutinise related-party dealings and establish the actual movement and utilisation of funds across the company’s domestic and overseas subsidiaries.
A publicly listed company is accountable to its shareholders and the public. Its management cannot expect transparency to be replaced by a favourable public image or institutional proximity. If the financial disclosures are accurate and the transactions commercially justified, Duraid Qureshi and HUM Network should have no difficulty providing a comprehensive, independently verifiable explanation. Until then, the gross and massive discrepancies in these filings demand serious answers.
@Duraidqureshi1
Faisal Afzal retweeted

Billions in financial questions, overseas accounts and massive CEO payouts! Public shareholders deserve answers, not excuses. Transparency and accountability are non-negotiable. Time to explain every rupee!
@Duraidqureshi1
🚨🚨Top breaking Investigative Dossier from UK exposes massive black money scandals of Duraid Qureshi & his money laundering empire run under cover of Hum Awards
An examination of official financial statements filed by HUM Network, records available through the Pakistan Stock Exchange, and corporate filings with the UK Companies House has raised serious questions about the financial practices of HUM Network and its CEO, Duraid Qureshi. The documents reveal a troubling pattern involving the valuation of overseas subsidiaries, undisclosed international event revenues, substantial inter-company balances, related-party payments, executive remuneration and tax adjustments. Taken together, these discrepancies raise fundamental questions about corporate governance, financial transparency and the treatment of public shareholders in a company listed on the Pakistan Stock Exchange.
It is worth noting that Duraid Qureshi has successfully maintained a visible presence in influential institutional circles, including frequent visits to the Ministry of Information and Broadcasting (MoIB) and ISPR. Such engagement has helped him maintain a cordial public and institutional profile.
However, the financial practices reflected in the company’s filings raise serious questions that cannot be answered through personal relationships, public appearances or a carefully cultivated corporate image. The issue is whether the management of a publicly listed company has been operating in the best interests of its shareholders or using complicated domestic and overseas corporate arrangements in ways that require closer regulatory scrutiny.
In September 2024, HUM Network organised an award show at London’s Wembley Arena. Subsequently, the company reduced the reported value of its 100% shareholding in its UK subsidiary, HUM Network UK, from PKR 95.9 million to zero, effectively recognising the entire investment as a loss in its Pakistani accounts while retaining full ownership of the subsidiary. What makes this write-down particularly questionable is that HUM Network’s UK sales increased by 22% during the same year, reaching PKR 334.3 million. How could the value of a wholly owned subsidiary be reduced to zero in the very year that business generated from the UK was growing substantially? Was this a genuine commercial loss, or does the accounting treatment warrant investigation?
The UK company’s accounts filed by Duraid Qureshi in March 2026 reveal further financial inconsistencies. Its bank cash balance had nearly doubled to £377,000, while outstanding liabilities exceeded £3.2 million and accumulated losses reached £1.958 million. More importantly, the company’s public filings did not include a Profit and Loss Account. By relying on the reporting exemptions available to small companies under UK law, the subsidiary was not required to publish detailed income and expenditure figures and also obtained exemption from statutory audit. Consequently, the actual financial performance of the Wembley event, including ticket-sale proceeds, sponsorship income, operational expenses and ultimate profitability, cannot be independently established from the publicly available accounts.
The financial treatment of inter-company transactions raises equally serious questions. After writing down the value of its UK subsidiary to zero, HUM Network’s Pakistani parent company also wrote off PKR 105.3 million owed by the same subsidiary, treating the outstanding trade receivable as irrecoverable. At the same time, the amount recorded as receivable from HUM Network’s Dubai-based subsidiary, HUM Network FZ LLC, increased from PKR 2.59 billion in 2024 to more than PKR 5.32 billion in 2026. This extraordinary increase warrants a detailed explanation regarding the nature of these transactions, the commercial purpose of the advances, the recovery arrangements and the ultimate location and utilisation of these funds. For a publicly listed Pakistani company, billions of rupees tied up in overseas subsidiaries cannot simply be treated as an internal accounting matter.
The Wembley award show itself raises fundamental questions about revenue disclosure and financial transparency. Despite the event involving thousands of tickets, no corresponding breakdown of ticket-sale proceeds has been established through the publicly available records examined. The only specific entry identified in Brent Council’s official records relates to 10 complimentary tickets, valued at £450, provided to local councillor Ajmal Akram. This does not account for the wider ticketing operation or the event’s overall financial performance. Equally concerning are the accounts of Alliance Advertising, the UK agency responsible for sponsorship arrangements for the event. Its public filings did not disclose a Profit and Loss Account and showed £1.5 million in outstanding receivables at year-end, despite reporting a zero bank cash balance. These figures raise questions about the actual collection, transfer and accounting of sponsorship revenues. There is also no identifiable accounting entry, amount or receipt in the company’s annual report to substantiate the commitment associated with the 2022 Canada Awards Show to contribute ticket proceeds towards relief for Pakistan’s flood victims. Where did the promised contribution go, and what documentary evidence exists to establish that it was actually made?
The domestic financial picture is equally revealing. During FY2025, HUM Network reported production expenses of PKR 7.68 billion and made payments amounting to PKR 2.47 billion to affiliated family-owned production entities, including MD Productions and Momina & Duraid Films, within a single financial year. These substantial related-party transactions raise questions about the commercial basis of the payments, the pricing of production services, the selection of vendors and the safeguards in place to protect ordinary shareholders. In other words, while the company reports substantial production costs and accounting losses, billions of rupees are being paid to entities affiliated with its own management and family business interests. These transactions deserve independent examination to establish whether they were conducted at arm’s length and in the genuine commercial interests of HUM Network.
Perhaps the most striking contrast is Duraid Qureshi’s own remuneration. During FY2025, he received PKR 361.2 million in salary, bonuses and other benefits as CEO. This amounts to more than PKR 36 crore annually, or approximately PKR 3 crore per month when averaged across the year. While the company’s overseas investments and operations are being presented through substantial write-downs and accumulated losses, its chief executive continues to receive exceptionally high personal remuneration. The obvious question is why public shareholders should bear the financial consequences of questionable overseas investments and reported losses while the CEO continues to receive such substantial financial rewards. The distinction between corporate losses and executive earnings is particularly important: shareholders’ capital is exposed to the company’s financial risks, whereas executive remuneration may continue to be paid regardless of the performance of individual overseas ventures.
Despite these substantial expenses and executive payouts, HUM Network’s parent company reported a net tax credit of PKR 25.2 million rather than an income tax liability, following accounting losses and adjustments. This raises further questions about the basis of the tax credit, the nature of the adjustments and whether the reported losses accurately reflect the underlying commercial performance of the business.
The central issue is therefore not simply whether HUM Network has incurred losses. It is whether those losses, overseas financial arrangements, related-party payments and executive benefits have been properly accounted for and transparently disclosed to the company’s public shareholders. Why was the UK subsidiary valued at zero despite rising UK sales? Why was a substantial receivable from that subsidiary written off? Why have the amounts recorded against the Dubai subsidiary more than doubled? Where are the detailed revenue and expenditure accounts for the Wembley show? What happened to the ticketing and sponsorship proceeds? What documentary evidence supports the promised contribution to Pakistan’s flood victims? And what independent safeguards ensure that billions of rupees paid to family-affiliated production companies represent genuine, fairly priced commercial transactions?
There is also a fundamental question of accountability: how can a CEO of a publicly listed company justify receiving more than PKR 36 crore annually in remuneration while shareholders are left to absorb the consequences of reported losses, overseas write-downs and questionable financial arrangements?
These are serious questions arising from corporate filings and financial disclosures, not conclusions that should be prejudged without a full investigation. The Pakistan Stock Exchange, Securities and Exchange Commission of Pakistan, Federal Board of Revenue, National Accountability Bureau (NAB) and other relevant regulatory authorities should examine the transactions, obtain supporting bank records, scrutinise related-party dealings and establish the actual movement and utilisation of funds across the company’s domestic and overseas subsidiaries.
A publicly listed company is accountable to its shareholders and the public. Its management cannot expect transparency to be replaced by a favourable public image or institutional proximity. If the financial disclosures are accurate and the transactions commercially justified, Duraid Qureshi and HUM Network should have no difficulty providing a comprehensive, independently verifiable explanation. Until then, the gross and massive discrepancies in these filings demand serious answers.
@Duraidqureshi1
Faisal Afzal retweeted
دوسروں کے حساب کتاب پر سیاست کرنے والوں سے اب اپنے خاندان کے مالی معاملات پر بھی سوال ہوں گے۔ 15 سوالات، کئی سنگین دعوے اور جواب کا انتظار کرتی عوام!
#فضلو_اختجاج_ٹھس
#خاندانی_چور_فضلو

Faisal Afzal retweeted

Samaa News thought that by spreading fake propaganda, they could put Rana Sikandar Hayat on the back foot. But that was their biggest mistake!
They expected him to back down, but Rana Sikander Hayat did exactly the opposite. He came out on the front foot and gave them a strong response. No backing down, no pressure, no blackmailing!
A big salute to you @RanaSikandarH We need more leaders like you who know how to stand their ground❤️🔥

طلعت بھائی چینل بنانے کا پیسا کہاں سے آیا ؟ کبھی پارک ویو کے متاثرین پر پروگرام کیا ؟
بیشک آپ کی تنخواہ بڑھ گئی ہو گی اس پروگرام کے بعد مگر یاد رہے پڑھے لکھے لوگ سب جانتے ہیں- مشرف ، پرویز الٰہی ، عمران خان ، IPP, سب کو دھوکہ!
اور کونسی جماعت کا اپنا چینل ہے ؟ کہاتھا پیسوں کا نشہ اتار دوں گا! دیکھیں اتر رہا ہے 😂🙏