


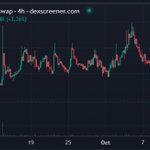
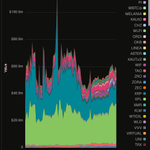


Not sure what's going on with base:0x0c03ce270b4826ec62e7dd007f0b716068639f7b, but chart looks like someone has been twapping out
Haven't followed the timeline recently, but are there doubts about the upcoming revenues for the vehicle routing algo?

MB 🦇🔊 retweeted

That’s also the typical shape of the forward curve until this year. A year ago it was in strict backwardation consistent with long-tendency discounts and expectations of incoming supply.
Even now you still get that backwardation on the front of the curve as on-demand/spot is still more expensive than 12-month reserved. But past 1 year longer-term rental rates begin to climb again which reflects expectations of higher future rental rates and maybe an unwillingness from providers to lock into long-term contracts. You can’t store it to supply into future either so it’s different from commodities like oil or crops.
Now part of this, esp the weird local twists and turns of the curves, obviously has to do with the immaturity of this market and could indeed exhibit certain seeming inconsistencies like you’d observe in oil or treasury curves when the market is distress.


MB 🦇🔊 retweeted

Galaxy posted $0.83 adjusted EPS vs. a $0.22 consensus. Nearly 4x.
Nice headline. But it's not why I bought more yesterday after the call.
Look at the slide: $569M of adjusted gross profit, $323M of net income, $455M of adjusted EBITDA. Big numbers, but most of it came from one place, the investment portfolio. It alone made $395M of that EBITDA.
Galaxy is really three companies under one ticker: a crypto financial firm, a data center developer, and that investment book.
Strip out the investment portfolio and the two operating businesses made $60M of adjusted EBITDA, up from about $1M in Q2. Their adjusted gross profit hit $150M, up from $86M.
That’s the part I care about most. It’s less exposed to price volatility and market cycles. But let me actually share my comments on everything they just shared.

ALT Galaxy's Q3 2026 at a glance slide: $569M adjusted gross profit, $323M net income, $455M adjusted EBITDA, $11B assets on platform, 12% trading volume growth, $79M from the first full quarter of leasing revenue.


MB 🦇🔊 retweeted

ethereum:0x76e222b07c53d28b89b0bac18602810fc22b49a8 is 5x leveraged ethereum:0x6982508145454ce325ddbe47a25d4ec3d2311933 minimum, with no risk of liquidation. Joe is a GENERATIONAL play.

This is the least talked about item that imo deserves a lot more attention that what it's getting
Would love to get more details on it soon
$glxy
@novogratz

MB 🦇🔊 retweeted

1. Well, I thought the call was good today. Definitly a full 180 compared to last quarter. Novo, Chris, and Tony, well done lads. Its clear as always $GLXY is executing as a business. Another $200M in buybacks is a good gesture, and will hopefully help provide a bottom here.
MB 🦇🔊 retweeted

Most data center landlords beg for tenants. Galaxy just told one no.
When power is the bottleneck, the guy holding the megawatts gets to be picky. Wild flex for a company the market was pricing like it was desperate a week ago $GLXY

Novogratz just clarified whats happening with the second tenant for Helios 2!
It turns out Galaxy walked AWAY from a Helios 2 lease this summer, passing because the power constraint got bigger
Mike Novogratz on the call today: "we ultimately decided not to move forward on the terms being considered"
He said the market for large-scale power data centers "has become increasingly constrained, while demand for capacity beginning in 2028 and beyond has strengthened"
Galaxy's president added that new power approvals are harder to get and competing projects are getting delayed, which limits how much compute can actually be delivered from 2028 to 2030
That makes Helios 2's 800+ MW of secured power worth more, not less
"we believe Helios 2 is an even more valuable asset today than it was just a few months ago"
And they're in no rush: "we're not going to compromise on terms just to meet an announcement date"
On top of a new tenant at a higher price incoming, they expect to exit 2027 at an $800-850M annualized leasing run rate
This is huge for Galaxy!


MB 🦇🔊 retweeted

$GLXY at $17 is a weird setup. You’re basically buying an AI data center company and getting a growing crypto business thrown in for free.
Galaxy reported earnings today. Some quick thoughts
The headline numbers look huge: $569M adj. gross profit, $455M adj. EBITDA, $323M net income. But most of it isn’t operating earnings.
If you look by segment:
Treasury & Corporate: $395M adj. EBITDA (vs –$78M last quarter), ~87% of the total.
It’s almost all mark-to-market gains on the investment book after two quarters of losses. Net digital assets & investments rose 48% to $1.72B.
Digital Assets: $71M adj. gross profit (+9%) but still –$9M adj. EBITDA.
Fundamentals are clearly healthy: trading volume +12% while the spot market shrank, the loan book +27% to $1.8B, and AUM + assets under stake +46% to $10.4B with >$160M of net inflows.
They’re gaining share. The problem is that it’s now 4 straight quarters of negative EBITDA, and the street doesn’t believe it can be reliably profitable in this market.
Data Centers: $79.1M leasing revenue, $68.7M adj. EBITDA (+498% QoQ).
It’s the first full quarter of Helios Phase I, right at the ~$80M/qtr guide with ~87% margins. Phase II (260 MW) is fully financed via $3.5B of notes, with deliveries starting Q2 2027. 830 MW at Helios II is still unleased. Galaxy walked away from a deal there because Texas power is getting scarce and they think they can get better terms.
Now the valuation and where I think it gets interesting
Phases I + II online = 393 MW leased to CoreWeave on 15-year contracts. At Phase I’s actual rate (~$2.4M revenue per MW per year) and ~89% margins, that’s ~$830M of run-rate EBITDA by late 2027.
15x seems fair for long-dated contracted leases, even with CoreWeave as the single tenant. Discounted back a year, since Phase II only starts delivering in Q2 2027:
EV: ~$12.5B, or ~$11.3B discounted
– Debt: ~$7.0B ($1.3B Phase I facility + $3.5B Phase II notes + $2.1B exchangeables)
Cash & stablecoins: ~$2.1B
= ~$6.5B equity, or ~$16.50/share
Market cap today: ~$6.5B.
So the market is pricing Helios and nothing else. The crypto franchise, the $1.7B investment book and the rest of the data center Biz are all at $0.
That feels too aggressive, even with 4 quarters of negative EBITDA. The core trading and lending business is strong. The real open question is how well Galaxy can monetize tokenization and RWAs. If they figure that out, you’re getting it for almost for free at these prices.
MB 🦇🔊 retweeted

Agree entirely. Think they did a good job addressing the three main items.. (i) new tenant at Helios II (seems very positive here, Ferraro notably more bullish than prior calls) (ii) balance sheet strength (underappreciated how they raised $1.6B+ roughly a year ago at top of crypto market) (iii) execution (to your point kinda impossible to rule out all of the regulatory risks but relative to peers I trust they're much more on top of things).
Don't think the "Fourth of July, knock on wood" debacle can be put to bed until a deal is actually signed but their explanation and rationale tracks entirely with everything else going on. It could turn out to be a very good thing they didn't sign something this summer right before financing costs increased in a pretty material way.. Have to imagine they can push for a higher unlevered yield on cost today versus 4-5 months ago (to pass through higher financing costs).
April 2027 for studied load allocations also a nice little positive surprise (I would have guessed summer 2027).. And "mid-2028" for first phase of Helios II also suggests all of the TSP/utility work is progressing well.
Crazy to think one of their peers had to raise an $850MM convert during a -50%+ drawdown because they're 40% over budget on their build costs.. Puts into perspective how strong of a position GLXY is in authorizing another $200MM buyback. If you read through the S&P ratings analysis on Helios I Phase II financing you can see they actively addressed these types of risks that other folks seemed to take gambles (and lose) on.
Also FWIW I think CRWV would almost certainly accept data halls without backup diesel gens (their customers would prob rather have capacity w/ risk of downtime vs. no capacity online at all).

We are all trying to find the bottom on RHC
Gave another shot at $stonkbroker today
the building is still in process and I like all the tools being built even if they are not fully utilized yet

MB 🦇🔊 retweeted

Great quarter for $GLXY and mgmt said most of the right things. This stock is insanely cheap IMO no matter how you slice it.
Unfortunately, the market continues to think GLXY is just a derivative of $CRWV
The correlation between the two has never been higher.
In order for the stock to really move higher and untether itself from CRWV, GLXY has to
A) sign a new tenant / diversify
B) spin out the data center business
C) remind the market that it also has a large and profitable crypto business that gives investors exposure to the growth of stablecoins, DeFi and RWA tokenization.
Does no good to just be labeled “cheaper CRWV with a stronger balance sheet”.


MB 🦇🔊 retweeted

binance spot continuing to blast towards the tail end of the session.
this behavior has been interesting to see past few sessions, a significant amount of aggressive spot buying on binance but the relative impact on price hasn't been appreciable so far.
let's atleast see a squeeze leg.
ltf hanging around composite vah so if momentum loss again it stays within rotational range.
~82 clean up above

MB 🦇🔊 retweeted

i've been wondering who paid for this ad urging public company CEOs to opt out from third-party tokenization
at the bottom right of the image, it says "Paid for by Common Sense Leadership Fund" -- this is a republican-aligned dark money non profit... why would they run this?


MB 🦇🔊 retweeted

Added a new HYPE Engine Vault buybacks chart to the @Dune for @NestExchange.
The HYPE Engine Vault is a big reason for the 85+% lock rate. It emphasizes maximum alignment for tokenholders who always receive a high voting APR, compound into more veNEST, and get HYPE.
KNTQ next


The market has not understood this important part of the equation yet
$GLXY
$HUT
$WULF
$CIFR
In addition, the exec team from $GLXY have not sold a single share in 2026
@novogratz

In today’s AI buildout everyone has been diluting shareholders with equity raises and convertible notes. I am only aware of one company ($GLXY) who has been actively buying back their stock this year. They exhausted the $200m buyback earlier this month and the board authorized another $200m program.
This says i) Galaxy is well capitalized with a strong balance sheet and ii) they believe their stock is not trading at fair value and have drawn a line in the sand.
If you can’t understand the asymetric trade here and are one of the 35m shares short I can’t help you.
I’m anticipating a number of insider purchase disclosures in the coming weeks as well.
Long and strong 💪
MB 🦇🔊 retweeted

In today’s AI buildout everyone has been diluting shareholders with equity raises and convertible notes. I am only aware of one company ($GLXY) who has been actively buying back their stock this year. They exhausted the $200m buyback earlier this month and the board authorized another $200m program.
This says i) Galaxy is well capitalized with a strong balance sheet and ii) they believe their stock is not trading at fair value and have drawn a line in the sand.
If you can’t understand the asymetric trade here and are one of the 35m shares short I can’t help you.
I’m anticipating a number of insider purchase disclosures in the coming weeks as well.
Long and strong 💪