

Stockholm
Joined January 2010
- Tweets5.3K
- Following301
- Followers871
- Likes3.5K


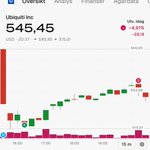

Aha, they milk the cow for 500 MUSD by diluting the stock. Guess someone knew it a bit early today.

$AAOI was up almost 10% in pre-markets but trade almost flat now. If Chinese competition is blocked out, they should get bigger share of US market.
20

Helt orimligt att Jensen skulle kunna bli VD för Nvidia igen före alla anklagelser är nedlagda. Dvs alla utfrågningar och utredningar måste ha sin gång först. Därefter, när allt är nedlagd, om så blir fallet, finns en liten liten möjlighet för comeback.
3
264
$AAOI was up almost 10% in pre-markets but trade almost flat now. If Chinese competition is blocked out, they should get bigger share of US market.
Det låter som att det värsta är förbi för Klarna nu. Nu har arbetet påbörjats med att förädla kundstocken och höja marginalen i affären. Ser vi sekventiella förbättringar Q-Q några kvartal framåt kan det bli riktigt bra.
2
10
2,064
Klarna har nu rapporterat och bottarna som handlar i förhandeln verkar ha svårt att förstå om det är en beat eller miss. Uppfriskande att se att en människa skulle hinna fynda som är påläst och agerar på informationen.
7
746
$KLAR Klarna hoppade upp i förhandeln precis men ser ingen Q3-rapport ännu.
5
17
6,279
Tog lunch och såg då att semis var ner 1-3% i förhandeln. Tillbaka bakom skärmarna och de är upp några procentenheter i förhandeln. Vad hände?
178
Uber kanske inte ska stiga igen. Svårt att konkurrera med förarlösa taxis.

Dude Uber is crazy desperate in Austin rn. These prices are lower than what Tesla was offering before Cybercab launch. How is Uber going to make any money on this? What does the driver get on this trip?
On a side note, Tesla fixing the navigation issue I mentioned earlier brought prices down for this trip for them too
Tesla is going to destroy Uber if they keep bringing Cybercab prices down in Austin like this. This is actually pretty crazy


214
Antrophic IPO kanske flyger men på sikt tror jag inte de amerikanska labben är en bra investering.
efn.se/darfor-ger-kina-bort-…

165
Mitt näst största innehav $KLAR flyger idag efter en tråkig period. Bra motvikt mot AI-bolagen som mår sämre idag.
1
15
1,080
Swedish Analyst retweeted

Vem vinner AI racet??
USA leder AI frontier utvecklingen (allegedly, jag har ingen aning). Och oavsett så, DeepSeek v4.1 har 10x token användning jmf Claude Opus 5.5. Det finns ett case att argumentera för att ekonomin i stort vinner på bred adoption. Då blir riktigt bra, riktigt billiga open source modeller svåra slå. 👇

Swedish Analyst retweeted

$CBRS Q3 2026 earnings: Cerebras raises its cloud sales plan, but cash burn grows
Cerebras Systems, a maker of wafer-sized artificial intelligence chips, is turning its $26.1 billion contract backlog into cloud sales faster than its earlier plan promised, while stock grants and customer warrant discounts push standard accounting losses deeper. Core revenue excluding those items rose 70% from a year ago to $231 million, driven by cloud sales that nearly quadrupled. Chief executive Andrew Feldman lifted the full-year core revenue target by $65 million and set the fourth-quarter plan at $320 million at the middle of the range, well above what the company's prior outlook pointed to.
• Core revenue, excluding one-offs: $𝟐𝟑𝟎.𝟗𝐌 (+70% from a year ago; beat $214–216M plan)
• Standard GAAP revenue: $𝟐𝟏𝟎.𝟖𝐌 (+55% from a year ago after $36M warrant discount)
• Contracted backlog (RPO): $𝟐𝟔.𝟏𝐁 (up $0.7B from last quarter; 700MW power secured)
• Full-year core revenue outlook: 𝐑𝐚𝐢𝐬𝐞𝐝 $𝟔𝟓𝐌 (to $940–960M; Q4 plan set at $310–330M)
⚖️ 𝐕𝐞𝐫𝐝𝐢𝐜𝐭: 🟢 Bullish
The story got better because the two main operational hurdles — third-party data center handovers and margin pressure from rented systems — cleared ahead of schedule. Securing 700 megawatts of power and installing its own lower-cost systems allowed management to project a 48% core gross margin and break-even core operating profit for the fourth quarter, erasing the fourth-quarter loss increase implied three months ago. The bad news: third-quarter free cash outflow reached $839 million on heavy equipment buying, dilute share count quadrupled from a year ago, and $1.1 billion in customer stock warrants held standard gross margin down at 20%.
The question now is whether turning on new data centers will turn into real cash profit or stay absorbed by customer equity discounts and equipment bills. One view is that tripling core revenue in 2027 and pairing chips withOracle and Amazon will quickly cover fixed costs; the other is that OpenAI still dominates the backlog and pays partly with loan credits and warrant discounts. The customer concentration footnote in the third-quarter filing and fourth-quarter capital spending will tell.
[Model: Gemini 4 Argon. Full article with charts - link in bio]
🐂 𝐁𝐮𝐥𝐥 𝐂𝐚𝐬𝐞
🟢🟢 𝐍𝐞𝐰 𝐃𝐚𝐭𝐚 𝐂𝐞𝐧𝐭𝐞𝐫𝐬 𝐋𝐢𝐟𝐭 𝐅𝐨𝐮𝐫𝐭𝐡-𝐐𝐮𝐚𝐫𝐭𝐞𝐫 𝐏𝐥𝐚𝐧
Cerebras builds giant computer chips for artificial intelligence and rents them out through its own data centers. Because customers have already signed $26.1 billion in multi-year contracts, revenue grows as fast as the company can wire up new buildings. This quarter the chipmaker added 100 megawatts of contracted power, bringing its total secured capacity to 700 megawatts for delivery by the end of 2027, including new sites in Norway and Finland.
Those power hookups are arriving ahead of schedule. Management set the fourth-quarter core revenue outlook (which excludes stock grants to customers and pass-through building costs) at $310 million to $330 million, up 39% from the third quarter at the middle of the range. By our math, that is $51 million above what the previous full-year plan implied for the fourth quarter, and chief executive Andrew Feldman said the team continues to "expect to triple revenue in 2027".
What to watch: fourth-quarter core cloud revenue against this $320 million middle target. Hitting that step-up will confirm that third-party data centers are turning on power on time to support the 2027 tripling goal.
🟢🟢 𝐎𝐰𝐧𝐞𝐝 𝐒𝐲𝐬𝐭𝐞𝐦𝐬 𝐋𝐢𝐟𝐭 𝐂𝐨𝐫𝐞 𝐌𝐚𝐫𝐠𝐢𝐧𝐬 𝐭𝐨 𝐁𝐫𝐞𝐚𝐤-𝐄𝐯𝐞𝐧
Three months ago, management warned that third-quarter core gross margin would dip to a low point between 38% and 40% because the business was renting back older hardware from customers to meet cloud demand. Instead, core gross margin rose to 41.0%, up from 40.6% in the second quarter. Cloud gross margin excluding one-offs climbed 5.1 percentage points from last quarter to 46.9%, offsetting a drop in hardware margin to 31.0%.
The company now expects fourth-quarter core gross margin to jump to between 47% and 49% as new data centers filled with its own lower-cost systems come online. That 7-point improvement, combined with higher sales, lifts the fourth-quarter core operating margin outlook to between minus 1% and plus 1%, erasing the $71 million fourth-quarter operating loss that the prior annual plan implied by our math.
What to watch: whether core operating margin reaches positive territory in the fourth quarter. A positive reading will prove that new company-owned data centers carry enough profit to cover research spending.
🟢 𝐎𝐫𝐚𝐜𝐥𝐞 𝐚𝐧𝐝 𝐚 𝐓𝐨𝐩 𝐂𝐥𝐨𝐮𝐝 𝐉𝐨𝐢𝐧 𝐭𝐡𝐞 𝐑𝐨𝐬𝐭𝐞𝐫
Until recently, nearly all of Cerebras's $25.4 billion contract backlog sat with OpenAI, while two buyers accounted for 66% of second-quarter revenue. This quarter the company signed commercial deals with two additional major cloud providers: Oracle will integrate Cerebras chips into Oracle Cloud Infrastructure in 2027, and management announced "an important cloud deal with a top three hyperscaler" with details to follow next year.
Finance chief Bob Komin added that the sales team won consumer platform Bilt and several smaller AI clouds, and "saw our pipeline for high-speed AI inference increase by more than 10x in the quarter". Remaining performance obligations — contracted revenue not yet delivered — rose by $700 million from last quarter to $26.1 billion even after recognizing $211 million in quarterly sales, showing that new bookings are outpacing deliveries.
What to watch: the customer concentration footnote in the upcoming third-quarter filing. A drop in the share of revenue from the top two buyers below 66% will show that new enterprise wins are diversifying sales before the big cloud partnerships launch in 2027.
🟢 𝐂𝐡𝐢𝐩 𝐏𝐚𝐢𝐫𝐢𝐧𝐠𝐬 𝐌𝐮𝐥𝐭𝐢𝐩𝐥𝐲 𝐃𝐚𝐭𝐚 𝐂𝐞𝐧𝐭𝐞𝐫 𝐎𝐮𝐭𝐩𝐮𝐭
Running an AI model takes two steps: reading the user's prompt and generating the answer word by word. Cerebras now splits those jobs across different hardware, pairing standard graphics chips for the prompt with its own wafer-sized chips for the response. The company became the "First to deliver production scale heterogeneous disaggregated inference offering", turning a lab project promised for the fourth quarter into a live commercial product ahead of schedule.
Splitting the workload increases the number of AI words a data center can produce by up to five times for the same electrical power, generating "more profit per MW for cloud owners and lower cost per token for AI users". Meanwhile, the next-generation Wafer Scale Engine 5 processor returned from the factory and entered system testing in under five months, keeping the CS-5 system on track for early summer 2027.
What to watch: the launch of split-chip inference on Amazon Web Services Bedrock in the first quarter of 2027. Live deployment on Amazon's cloud will test whether third-party cloud owners adopt the paired setup as a standard offering.
🐻 𝐁𝐞𝐚𝐫 𝐂𝐚𝐬𝐞
🔴🔴 𝐂𝐮𝐬𝐭𝐨𝐦𝐞𝐫 𝐖𝐚𝐫𝐫𝐚𝐧𝐭𝐬 𝐚𝐧𝐝 𝐒𝐭𝐨𝐜𝐤 𝐆𝐫𝐚𝐧𝐭𝐬 𝐄𝐫𝐚𝐬𝐞 𝐏𝐫𝐨𝐟𝐢𝐭
Management highlights core financial results, which beat the company's plan across every line. Under standard accounting, however, profitability moved the other way because Cerebras gives big customers like OpenAI and Amazon cheap stock warrants as an incentive to buy its services. Accounting rules treat those warrants as a discount, subtracting $36.4 million from third-quarter revenue and cutting standard hardware gross margin to 11.0% from 50.4% a year ago.
• Standard gross margin: 20.0%, down 20.6 percentage points from a year ago and 21.0 points below core gross margin
• Research and development: 84.4% of revenue, up 42.2 percentage points from a year ago on $81.0 million of employee stock grants
• General and administrative overhead: 26.4% of revenue, up 23.8 percentage points from a year ago on $36.6 million of stock grants
• Unamortized customer warrant asset on the balance sheet: $1.09 billion, up from $152.4 million at the end of 2025
Because $1.09 billion in customer warrant discounts still sits on the balance sheet waiting to be subtracted from future bills, the gap between core and standard revenue will persist for years. Standard operating loss reached $224.1 million, or minus 106.3% of revenue, compared with a core operating loss of $33.1 million.
What to watch: fourth-quarter customer warrant amortization against the $36.4 million recorded this quarter. As new OpenAI data centers turn on in the fourth quarter, larger warrant deductions could keep standard gross margin near 20% even as core gross margin approaches 48%.
🔴🔴 𝐒𝐡𝐚𝐫𝐞 𝐂𝐨𝐮𝐧𝐭 𝐐𝐮𝐚𝐝𝐫𝐮𝐩𝐥𝐞𝐬 𝐚𝐧𝐝 𝐂𝐚𝐬𝐡 𝐁𝐮𝐫𝐧 𝐆𝐫𝐨𝐰𝐬
Building
Watching a cloud business that is "among the largest non-hyperscaler AI clouds" requires heavy upfront spending before customers pay their monthly bills. By our math, third-quarter cash used in operations widened to $341.4 million from $59.8 million in the second quarter, driven by a $546.0 million nine-month jump in prepaid expenses and a $181.3 million rise in unpaid customer bills. Cash capital spending on equipment reached $497.2 million in the quarter, pushing third-quarter free cash outflow to $838.6 million.
At the same time, the May initial public offering, preferred stock conversions, and the exercise of 10 million OpenAI warrants in July lifted the average diluted share count to 238.9 million, up 58% from the second quarter and more than four times last year's 54.0 million. Even if Cerebras hits break-even core operating profit next quarter, Equipment bills and customer warrant exercises will keep draining cash and expanding the share count.
What to watch: fourth-quarter purchases of property and equipment against this quarter's $497.2 million outlay. If capital spending stays near $500 million a quarter to build out the 700 megawatts of power, annual cash burn will exceed $1.5 billion despite the $7.8 billion cash cushion.
🔴 𝐑𝐢𝐬𝐤𝐬 𝐭𝐡𝐢𝐬 𝐪𝐮𝐚𝐫𝐭𝐞𝐫 𝐝𝐢𝐝𝐧'𝐭 𝐚𝐧𝐬𝐰𝐞𝐫
Four standing concerns from earlier filings cannot be checked until the full quarterly report arrives.
• Reliance on OpenAI and top buyers: the release does not state how much of third-quarter sales or the $26.1 billion backlog came from OpenAI; the quarterly filing's customer footnote will show whether sales outside OpenAI grew from $123.3 million last quarter.
• Off-balance-sheet data center leases: on-balance-sheet lease liabilities rose from $261.8 million at year-end to $621.1 million, and new Nordic sites likely added to the $2.3 billion of uncommenced lease commitments disclosed last quarter.
• Non-cash loan repayments: the OpenAI working capital loan balance fell by $89.2 million in the quarter to $829.1 million, indicating that a large slice of cloud revenue was settled via loan credits rather than cash.
• Inventory write-downs and chip rivalry: the release omits any excess inventory charges ahead of CS-4 full production, while graphics-chip makers continue to target inference speed.
— • — • —
💲 𝐎𝐭𝐡𝐞𝐫 𝐊𝐏𝐈𝐬
𝐃𝐞𝐟𝐞𝐫𝐫𝐞𝐝 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 (𝟐𝟔𝐐𝟑): $𝟔𝟖𝟕.𝟔 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
Total deferred revenue — upfront payments and financing credits for cloud services not yet delivered — rose 64.4% from the second quarter's $418.3 million and more than quadrupled from $166.9 million at the end of 2025. The non-current portion jumped from $244.5 million to $453.3 million as multi-year data center contracts approached deployment.
𝐂𝐚𝐬𝐡 𝐚𝐧𝐝 𝐦𝐚𝐫𝐤𝐞𝐭𝐚𝐛𝐥𝐞 𝐢𝐧𝐯𝐞𝐬𝐭𝐦𝐞𝐧𝐭𝐬 (𝟐𝟔𝐐𝟑): $𝟕.𝟖𝟎 𝐛𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
Total cash, restricted cash and investments declined by $801.4 million from $8.61 billion at the end of June. The chipmaker raised $6.23 billion from its May initial public offering and $1.01 billion from a preferred stock sale earlier in the year, and spent $838.6 million in third-quarter free cash outflow to fund data center equipment and working capital.
𝐖𝐨𝐫𝐤𝐢𝐧𝐠 𝐜𝐚𝐩𝐢𝐭𝐚𝐥 𝐥𝐨𝐚𝐧 (𝟐𝟔𝐐𝟑): $𝟖𝟐𝟗.𝟏 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇘ decelerating
The customer working capital loan from OpenAI fell from $918.2 million in June and $982.9 million in March. Because the loan is repaid by crediting OpenAI's monthly cloud bills and accrues non-cash interest ($57.2 million over nine months), the falling debt balance lowers future cash inflows from the backlog.
— • — • —
🔮 𝐆𝐮𝐢𝐝𝐚𝐧𝐜𝐞
𝐐𝟒 𝟐𝟎𝟐𝟔 𝐂𝐨𝐫𝐞 𝐫𝐞𝐯𝐞𝐧𝐮𝐞: $𝟑𝟏𝟎–𝟑𝟑𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
New. The plan calls for core revenue to rise 38.6% from the third quarter at the $320 million middle of the range. By our math, that is $51.2 million above the $268.8 million fourth-quarter figure that the previous full-year outlook pointed to, driven by new company-owned data centers turning on in the quarter.
𝐐𝟒 𝟐𝟎𝟐𝟔 𝐂𝐨𝐫𝐞 𝐠𝐫𝐨𝐬𝐬 𝐦𝐚𝐫𝐠𝐢𝐧: 𝟒𝟕–𝟒𝟗% ⇗ accelerating
New. The outlook has core gross margin jumping 7.0 percentage points from the third quarter's 41.0% at the 48.0% middle of the range. That compares with the 42.3% fourth-quarter rate implied by last quarter's annual plan, as lower-cost owned systems replace rented customer hardware.
𝐐𝟒 𝟐𝟎𝟐𝟔 𝐂𝐨𝐫𝐞 𝐨𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐦𝐚𝐫𝐠𝐢𝐧: (𝟏%) 𝐭𝐨 𝟏% ⇗ accelerating
New. Management expects the business to reach break-even core operating profit at the middle of the range, up from minus 14.3% in the third quarter and minus 16.0% in the second. That removes the minus 26.3% fourth-quarter operating margin drop that the prior annual outlook implied.
𝐅𝐘 𝟐𝟎𝟐𝟔 𝐂𝐨𝐫𝐞 𝐫𝐞𝐯𝐞𝐧𝐮𝐞: $𝟗𝟒𝟎–𝟗𝟔𝟎 𝐦𝐢𝐥𝐥𝐢𝐨𝐧 ⇗ accelerating
🠅 raised from $880–890 million
Raised. The middle of the full-year range moved up by $65 million to $950 million, or about 87% growth from 2025 by our math. It is the second raise this year and is more than twice the size of last quarter's $25 million increase, passing through the $15.9 million third-quarter beat and adding $49.1 million to the fourth quarter.
𝐅𝐘 𝟐𝟎𝟐𝟔 𝐂𝐨𝐫𝐞 𝐠𝐫𝐨𝐬𝐬 𝐦𝐚𝐫𝐠𝐢𝐧: 𝟒𝟐–𝟒𝟒% ⇗ accelerating
🠅 raised from 41–43%
Raised. The full-year target moved up by 1 percentage point to 43.0% at the middle of the range, following a 2.5-point raise last quarter from the initial 38% to 41% plan.
𝐅𝐘 𝟐𝟎𝟐𝟔 𝐂𝐨𝐫𝐞 𝐨𝐩𝐞𝐫𝐚𝐭𝐢𝐧𝐠 𝐦𝐚𝐫𝐠𝐢𝐧: (𝟏𝟎%) 𝐭𝐨 (𝟖%) ⇗ accelerating
🠅 raised from (19%) to (17%)
Raised. Management lifted the full-year margin plan by 9 percentage points at the middle of the range to minus 9.0%, after an 11-point raise last quarter from the initial minus 30% target. With nine-month core operating loss at $70.2 million, the annual middle target leaves a $15.3 million loss for the fourth quarter by our math, even more cautious than the break-even fourth-quarter plan.
𝐅𝐘 𝟐𝟎𝟐𝟕 𝐂𝐨𝐫𝐞 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐠𝐫𝐨𝐰𝐭𝐡: 𝟑𝐱 𝐅𝐘 𝟐𝟎𝟐𝟔 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 ⇗ accelerating
🠆 unchanged from More than triple FY 2026 revenue
Unchanged in rate, higher in dollars. Chief executive Andrew Feldman reiterated the plan to triple revenue in 2027. Because the 2026 base moved up by $65 million to $950 million at the middle of the range, tripling that base now points to $2.85 billion in 2027 core revenue by our math, up from $2.66 billion under the prior plan.
— • — • —
❓ 𝐊𝐞𝐲 𝐐𝐮𝐞𝐬𝐭𝐢𝐨𝐧𝐬
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐨𝐟 𝐐𝟑 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐚𝐧𝐝 𝐛𝐚𝐜𝐤𝐥𝐨𝐠 𝐜𝐚𝐦𝐞 𝐟𝐫𝐨𝐦 𝐎𝐩𝐞𝐧𝐀𝐈?
Two buyers made up 66% of second-quarter sales and OpenAI held most of the $25.4 billion backlog. Without the quarterly filing's customer table, investors cannot tell if sales outside OpenAI rebounded from $123 million last quarter.
𝐖𝐡𝐚𝐭 𝐚𝐫𝐞 𝐭𝐡𝐞 𝐭𝐞𝐫𝐦𝐬 𝐚𝐧𝐝 𝐭𝐢𝐦𝐢𝐧𝐠 𝐨𝐟 𝐭𝐡𝐞 𝐧𝐞𝐰 𝐭𝐨𝐩-𝐭𝐡𝐫𝐞𝐞 𝐜𝐥𝐨𝐮𝐝 𝐝𝐞𝐚𝐥?
Management announced a cloud deal with an unnamed top-three cloud provider but deferred details to next year. Whether the agreement includes customer stock warrants or upfront hardware commitments will determine its impact on standard gross margin.
𝐖𝐡𝐲 𝐝𝐨𝐞𝐬 𝐭𝐡𝐞 𝐚𝐧𝐧𝐮𝐚𝐥 𝐦𝐚𝐫𝐠𝐢𝐧 𝐩𝐥𝐚𝐧 𝐢𝐦𝐩𝐥𝐲 𝐚 𝐐𝟒 𝐥𝐨𝐬𝐬 𝐰𝐡𝐞𝐧 𝐐𝟒 𝐢𝐬 𝐠𝐮𝐢𝐝𝐞𝐝 𝐭𝐨 𝐛𝐫𝐞𝐚𝐤-𝐞𝐯𝐞𝐧?
By our math, the minus 9% middle of the full-year core operating margin outlook implies a $15 million fourth-quarter loss, while the fourth-quarter outlook sits at break-even. Management did not explain the 5-point gap between the two ranges.
𝐇𝐨𝐰 𝐦𝐮𝐜𝐡 𝐜𝐚𝐬𝐡 𝐜𝐚𝐩𝐞𝐱 𝐢𝐬 𝐥𝐞𝐟𝐭 𝐭𝐨 𝐛𝐮𝐢𝐥𝐝 𝐭𝐡𝐞 𝟕𝟎𝟎𝐌𝐖 𝐨𝐟 𝐝𝐚𝐭𝐚 𝐜𝐞𝐧𝐭𝐞𝐫𝐬?
Cash purchases of property and equipment jumped to $497 million in the third quarter, driving free cash outflow to $839 million. Management has not stated when quarterly equipment spending will peak or how much of the 700 megawatts is already paid for.

Swedish Analyst retweeted

Altså, hva skal man si. Dette var rett og slett et helt insane kvartal fra $MORROW.
21,5% rote, 0,45 i eps fra videreført drift og halvparten av synergiene på run-rate. 2028-målet om eps over 2 sek kan nås på run-rate allerede i q4 2026…
2028-ambisjonene lever farlig. Bare å nyte.


I morgen blir et ganske historisk kvartal for robinhood:0x710a0414dc599112987515ac8d76e0cd28546bc1. Jeg har 168m sek i pbt, hele 68m mer enn i q2 og 77m y/y. Til sammenligning økte kvartalsresultatet «bare» 33m fra q1 2024 til q2 2026 til sammen. Hoppet skyldes selvsagt medmera, men det er nettopp derfor morgendagen blir så interessant.
Jeg ligger nesten 28% over snittet av de tre megleranslagene jeg har sett. Enten har jeg oversett noe, eller så undervurderes inntjeningen ganske kraftig. Har forsøkt å gå grundig gjennom begge bankene og bygge opp det jeg mener er et realistisk estimat, ikke et bull-scenario i mine øyne. Blir faktisk ikke overrasket om vi ser over 170m.
Andre ting som blir interessante i morgen er synergiene, NPL-salgene, kapitallok og muligheten for høyere 2028-ambisjoner. Synes ikke sistnevnte hadde vært en overraskelse. Bilde under viser mine estimater for q3.
