
Investing @ Rational Equity. Engaged in a titanic struggle against a number.
Mumbai
Joined July 2010
- Tweets74
- Following120
- Followers121
- Likes36

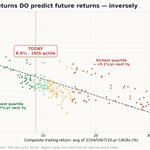


Nifty has done nothing for 2 years. Ran the numbers on what that historically means.
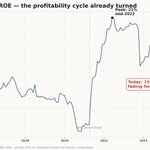
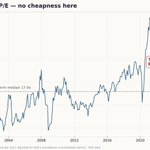
Since 2000, whenever avg of trailing 2-10yr returns was this low, next 5 years gave 13-24% CAGR. Sounds like a buy signal.
Except this time the earnings side bothers me. A thread :

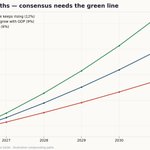
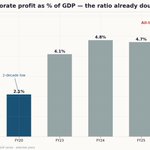
Putting it together - consensus is building 12-13% earnings growth. For that, profit share of GDP has to keep making new all time highs every year. Possible, but that’s the bull case, not the base case.
Base case to me is 8-10% earnings, similar returns. Decent. Not the 2020-24 experience.


In fact silver fell 50 percent and SILJ fell about 35 percent

#Gold & #silver miners just flashed signals not seen since the 2015 bear market bottom. Here's what the smart money is telling us:
The correction everyone fears may already be over.
Gold fell 28% from its Jan top. Historically, that kind of move crushes miners 2x or more — like 2022, when gold fell 22% and miners (HUI) collapsed 44%.
This time? HUI fell only 33%.
That's not weakness. That's the sector being held by long-term, conviction investors — not traders.
The sentiment data is screaming capitulation:
→ Daily Sentiment Index (DSI) hit 14 - near record bearishness
→ Gold Miners Bullish Percent Index hit ZERO - last seen at the 2015 bear market bottom
→ Open interest in gold futures at historic lows
→ Multiple consecutive weekly ETF outflows
→ 20-day MA indicator showing classic positive divergence
Every single one of these, historically, has marked an important bottom.
Silver is sending the same signal.
The big picture thesis remains intact.
The paradigm shift that began in 2020 isn't over — we may be at its most explosive acceleration point.
The crowd is maximally bearish. That's usually when the real money gets made.
Not investment advice.
Nifty Midcap index is at an all time high while Nifty 50 is below the 200 DMA. The last time this happened was never.


Vivek Iyer retweeted

Why Iran's Hormuz toll proposal isn't bluster
Hormuz carries 21 mb/d of oil and LNG
Total bypass capacity: ~5–6 mb/d
The remaining ~15 mb/d has nowhere to go
That gap is the leverage

Vivek Iyer retweeted
India’s IT sector is saturated with AI narrative.
But when we studied what companies are actually doing — talent, delivery models, productivity, and economics — a very different picture emerged.
The next winners in Indian IT are not where most investors are looking 🧵👇


Rare miss by an otherwise astute commentator. NIFTY Smallcap 100 Price to book at 2018 peak was 2x and 2025 trough is 4x. Base rates of success in picking multibaggers are going to be far lower in the next 5 years

Vivek Iyer retweeted

It’s a phase. In a few years, if the current massive capital expenditure in AI starts to look foolish, these buybacks will be viewed as savvy capital allocation decisions. The aggregate global capital expenditure in AI increasingly resembles a black hole, and much of it is poised to deliver subpar returns, if any at all. Identifying which projects will emerge as spectacular successes amid such a rapidly shifting landscape is akin to searching for a needle in a haystack.
In stark contrast, buybacks provide much greater certainty in outcomes compared to investing in an unpredictable industry rife with swift changes and fierce competition.
If investors are dissatisfied with the company’s capital allocation decisions regarding buybacks and would prefer that funds be channeled into AI investments, they always have the option to sell their shares on the market or in the buyback offer. They can then use the proceeds to invest in companies that are indeed focusing on AI. There’s nothing preventing them from doing that.
RT @ActusDei: A tiny AIF in GIFT city is betting big on gold miners. Their stocks have already rallied but the AIF sees further scope. The…