

DeFi researcher | BTC believer since ‘19 | I hunt and share onchain opportunities.
Joined October 2021
- Tweets34.9K
- Following35.2K
- Followers177K
- Likes28.8K





BLAZE retweeted

prediction markets traded $116b in contracts over the last 30 days @Kalshi alone grew 60%.
so when people say prediction market volume is falling, they are really talking about one exchange.
polymarket's international exchange traded $11.3b in june.
it traded $4.7b in september. its share of tracked volume went from about 59% in august 2025 to under 4% last week.
Get this, polymarket international has traded between $1.0b and $1.25b every week since early august.
it stopped shrinking months ago, and everyone else kept growing around it.
so why did it drop in the first place? four things line up with the timing.
>the world cup ended.
june was its biggest month since tracking began in august 2025, and the tournament ran from june 11 to july 19.
>trading stopped being free.
polymarket added taker fees to crypto markets in january, to sports in february, and to almost every other category on march 30.
>us traders got their own app.
polymarket us traded $13.5b in the last 30 days, up 94%, and 98% of it was sports.
>sports moved to regulated apps.
draftkings predictions and novig both more than doubled their volume in the last 30 days.
if you add both polymarket exchanges together, they traded $18.1b in contracts over the last 30 days
that is more than the $15.4b they traded together in june.
the volume did not disappear,
it moved to regulated us apps.
is the crypto version of prediction markets turning into a niche product, or is this just a reshuffle
Curious to hear your thoughts

BLAZE retweeted

𝗧𝗼𝗸𝗲𝗻𝗶𝘇𝗲𝗱 𝘀𝘁𝗼𝗰𝗸𝘀 𝗮𝗿𝗲 𝗺𝗼𝘃𝗶𝗻𝗴 𝗯𝗲𝘆𝗼𝗻𝗱 𝗵𝗼𝗹𝗱𝗶𝗻𝗴 𝗮𝗻𝗱 𝘁𝗿𝗮𝗱𝗶𝗻𝗴.𝗬𝗼𝘂 𝗰𝗮𝗻 𝗻𝗼𝘄 𝗯𝗼𝗿𝗿𝗼𝘄 𝗮𝗴𝗮𝗶𝗻𝘀𝘁 𝘁𝗵𝗲𝗺 𝗮𝗻𝗱 𝗯𝘂𝗶𝗹𝗱 𝗹𝗲𝘃𝗲𝗿𝗮𝗴𝗲𝗱 𝗲𝗾𝘂𝗶𝘁𝘆 𝗽𝗼𝘀𝗶𝘁𝗶𝗼𝗻𝘀 𝗱𝗶𝗿𝗲𝗰𝘁𝗹𝘆 𝗼𝗻𝗰𝗵𝗮𝗶𝗻.
I spent some time researching the latest development from @pendle_fi, and what caught my attention wasn't just the leverage. It was how three pieces of financial infrastructure are now working together on Base.
On October 22, Pendle introduced PendleLoop, allowing eligible users to build leveraged positions in tokenized US equities through @aave V4.
The supported assets include:
• AAPLc — Apple
• NVDAc — Nvidia
• GOOGLc — Alphabet
• TSLAc — Tesla
• AMZNc — Amazon
• MSFTc — Microsoft
• METAc — Meta
Here's what I found.
➊ 𝗙𝗶𝗿𝘀𝘁, 𝗵𝗼𝘄 𝗱𝗼𝗲𝘀 𝘁𝗵𝗲 𝗹𝗲𝘃𝗲𝗿𝗮𝗴𝗲 𝘄𝗼𝗿𝗸?
@aave already introduced lending markets for these equities in September.
@pendle_fi didn't create a new lending market. It built an interface that combines the transactions required to increase exposure.
Instead of manually buying tokens, supplying collateral, borrowing and repeating the process, users can manage the position through PendleLoop.
The mechanism works like this:
→ Purchase a tokenized stock.
→ Supply the tokens as collateral on $Aave V4.
→ Borrow $USDC against that collateral.
→ Use the borrowed $USDC to purchase additional stock tokens.
→ Repeat within the permitted collateral limits.
The result is a larger equity position than the capital initially committed.
At launch, available leverage ranged from approximately 2.6x to 4.2x, depending on the asset.
But leverage isn't free. Borrowing rates are variable, and a decline in collateral value can trigger liquidation.
➋ 𝗪𝗵𝗮𝘁 𝗮𝗰𝘁𝘂𝗮𝗹𝗹𝘆 𝗯𝗮𝗰𝗸𝘀 𝘁𝗵𝗲𝘀𝗲 𝘁𝗼𝗸𝗲𝗻𝗶𝘇𝗲𝗱 𝘀𝘁𝗼𝗰𝗸𝘀?
This is another detail worth understanding.
@coinbase Tokenized Stocks aren't simply synthetic assets following equity prices.
Each token represents a certificate issued by Coinbase Onchain SPV Ltd, with underlying shares held through Alpaca Securities (an SEC-registered broker-dealer).
The issuer holds those shares under a trust arrangement for token holders.
Corporate actions are also accounted for.
For example:
Dividends are reinvested into additional underlying shares (after applicable fees and taxes),rather than distributed directly to token holders.
This means the tokens provide economic exposure to the underlying equities, although their legal rights and redemption arrangements differ from holding ordinary shares through a brokerage account.
➌ 𝗡𝗼𝘄, 𝘄𝗵𝗮𝘁 𝗮𝗯𝗼𝘂𝘁 𝘁𝗵𝗲 𝗹𝗲𝗻𝗱𝗶𝗻𝗴 𝗺𝗮𝗿𝗸𝗲𝘁?
Aave V4's Equities Hub on @base supports the seven stocks as collateral for USDC borrowing.
At launch, the market had approximately:
• $29M in aggregate equity collateral caps.
• $32M USDC supply cap.
• $21M USDC borrow cap.
• Collateral factors ranging from 65% to 79%.
These are market limits, not actual deposits or borrowing volume.
And the collateral factors matter because they determine how much borrowing capacity each asset receives.
A token with a lower collateral factor generally requires more collateral for the same loan.
This also explains why PendleLoop cannot offer identical leverage across every stock.
➃ 𝗪𝗵𝗮𝘁 𝗱𝗼𝗲𝘀 𝘂𝘀𝗶𝗻𝗴 𝗣𝗲𝗻𝗱𝗹𝗲𝗟𝗼𝗼𝗽 𝗰𝗼𝘀𝘁?
Pendle is currently waiving its service fees on eligible non-PT looping positions until December 31, 2026.
However, that doesn't eliminate the cost of leverage.
Users still face:
• Variable USDC borrowing interest
• Transaction costs and slippage
• Liquidation risk when collateral values decline
Pendle has also announced borrowing incentives distributed through @Merkl_xyz.
Those incentives can reduce effective financing costs for qualifying positions, but they shouldn't be treated as permanent income.
➎ 𝗢𝗻𝗲 𝗿𝗶𝘀𝗸 𝗜 𝘁𝗵𝗶𝗻𝗸 𝗱𝗲𝘀𝗲𝗿𝘃𝗲𝘀 𝗺𝗼𝗿𝗲 𝗮𝘁𝘁𝗲𝗻𝘁𝗶𝗼𝗻
The lending market operates 24/7, but the underlying US stock market doesn't.
Aave uses Chainlink's tokenized equity price feeds, which publish prices 24/5.
During weekends and US market holidays, the feeds retain their last published prices.
That creates a pricing gap:
• A stock could experience a major development outside regular market hours
• while its onchain collateral valuation remains unchanged until the feed updates.
For leveraged positions, a sharp repricing when the feed resumes can become a liquidation problem.
So 24/7 access doesn't mean continuous price discovery or protection from market gaps.
✦ Conclusion
What I find significant is how the responsibilities are divided:
→ @coinbase handles the tokenized equity structure.
→ @aave provides the collateral and borrowing infrastructure.
→ @pendle_fi makes the transactions accessible through one interface.
Each component existed before this integration, but combining them reduces the work required to use tokenized equities in DeFi. And I think that distinction matters.
Issuing more tokenized stocks doesn't necessarily create more demand for them. The stronger test is whether holders are willing to supply those assets as collateral, borrow against them, and maintain positions after promotional incentives expire.
That's what I'll be monitoring:
▸ collateral deposits
▸ actual borrowing demand
▸ utilization
▸ how these markets behave during periods of equity volatility
Because the ability to tokenize a stock has already been demonstrated. Whether that stock can support a liquid, sustainable lending market is the more important question.

BLAZE retweeted

Last week I wrote about @RomeProtocol bringing Ethereum apps inside Solana. Did some more digging since then 👀...
Two things stood out.
👉Solana's Alpenglow upgrade just went live and because Rome runs natively inside Solana, every EVM transaction on @RomeProtocol now settles basically instantly ( Ethereum's tools, Solana's speed, no extra work needed!)
👉And it's not just theory. With Portus, people on Base and Polygon can already put their USDC to work in Kamino on Solana while signing on their own chain. They never even leave.
That's the part I liked most fam, not just another bridge you have to trust, but two worlds actually sharing the same market.
Rome wasn't built in a day, but it's coming together fast . Watching it closely and will keep you posted about their next steps!🏛️

BLAZE retweeted

Been keeping an eye on @RomeProtocol lately, and Portus is a pretty good example of why.
It started with Base, and now Polygon users can access Kamino lending on Solana too.
You can deposit USDC from your own chain, while Rome handles the interaction with Solana behind the scenes. Withdrawals even return to the same address.
This is where the whole “EVM inside Solana” idea starts to make sense to me.
Less about which chain you're using, more about what you can actually do with it.
Curious to see what they build next. 🏛️

BLAZE retweeted
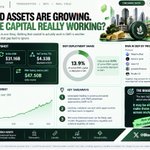
Tokenizing real world assets is one thing. Getting that capital to actually work in DeFi is another.
The latest RWA figures make that gap hard to ignore.
Here’s what stands out:
$34.44B in total onchain RWA AUM
$31.16B in active AUM
$4.33B deployed across DeFi
$19.82B in RWA perp open interest
$47.50B in daily RWA trading volume
Only around 13.9% of active RWA capital is currently deployed in DeFi.
And most of that activity is concentrated in a handful of protocols:
→ @Morpho Blue: $768.1M
→ @Kamino Lend: $423.1M
→ @Aave V3: $417.2M
→ @grovedotfinance: $394.7M
→ @pendle_fi V2: $351.5M
Together, they account for roughly $2.35B, more than half of the reported DeFi deployment.
Meanwhile, RWA perpetuals are attracting significant trading activity, with open interest approaching $20B.
These numbers measure different things, so they aren’t directly comparable. But they highlight an interesting trend: leveraged trading is growing alongside tokenization, while lending, collateral use, and yield opportunities still have room to expand.
Of course, not every tokenized asset can be freely used in DeFi. Regulatory restrictions, liquidity, and collateral eligibility all matter.
Still, the opportunity is worth watching.
The next big RWA opportunity may not be about who tokenizes the most assets.
It may be about which protocols make those assets genuinely useful across onchain financial markets.
BLAZE retweeted

Been off X for a month. Had to take care of a few things and spend some time learning and figuring life.
Now I'm back on the timeline.
More building.
More of me.
More learning.
Still growing. Still figuring it out. Still hungry for more.
We're not starting over. We're picking up where we left off. 🦅

BLAZE retweeted

$GRVT has burned 1.1M tokens, nearly 1% of its circulating supply.
But the burn isn’t the main story.
@grvt_io is building toward something bigger: one self-custodial balance where users can earn yield and trade across markets without leaving capital idle.
Earn, Stable Funding Perps, and Yield as Margin are all pieces of that plan.
The token mechanism and the product roadmap now sit beside each other. But the real test is whether the products attract sustained users and meaningful activity.
A burn can reduce supply. It can’t manufacture demand.
GRVT’s next chapter will be judged by adoption, not announcements.


BLAZE retweeted

Daily leaderboard on KICKFLIP. top 3 get paid every day.
flying cars are here. landing is still in beta.
Tried @PeergameEng new game. So fun, but I got greedy 😂
Reached 7.84, went for one more jump and lost it all. Should’ve cashed out, right?
Play here 👇
peergame.com/?campaignCode=0…
18+ only. Play responsibly.
🤝 Paid partnership
BLAZE retweeted

AI agents don't have to stay as tools
A specialized agent can become a service that other agents or users can actually hire
Developers can build an agent for a specific task but that capability needs somewhere to be discovered and used
That's where agent.family fits into the @termix_ai ecosystem
An agent can list its service, get discovered, take jobs, deliver the work and get paid
I think this creates an interesting path for monetization
Instead of keeping an agent inside one application, its capability can become a service available to potential clients
agent.family/r/PPFSAXCZ
Could specialized agents become a new kind of API economy?

BLAZE retweeted

Yoooo,
Just got approved as a Wired Creator!🎉
Honestly, this feels great. I love creating content, sharing my thoughts, and connecting with people across Web3.
Excited for what’s next. More to come🫡
creatorwire.xyz

BLAZE retweeted

.@grvt_io idle margin math, $10k for a month:
most perp venues: $0
3% bank: ~$25
grvt: up to 11% apy on eligible assets (~$90), potentially while it still backs your trades
institutional fixed income, a $160t+ market, going onchain. your keys.
margin shouldn't work for free.
BLAZE retweeted
Bitcoin has billions locked in DeFi. So why is so little of it being used for actual financial activity?
I was reviewing BTCFi data, and the concentration of capital caught my attention.
Bitcoin is attracting deposits, but lending and trading markets haven't developed at the same pace.
Here's what the numbers tell us.
➊ Babylon dominates Bitcoin's DeFi TVL
According to DefiLlama's October 23 snapshot:
• Bitcoin DeFi TVL: $4.37B
• Babylon: $3.34B
• Share of total TVL: ~76%
@babylonlabs_io has attracted substantial $BTC through native staking.
But there's an important distinction between capital being locked and capital being actively used.
Staking can secure networks and generate rewards without creating corresponding demand for lending or trading.
➋ @Stacks is worth examining for a different reason
Its Q3 ecosystem report highlighted:
• 735 $BTC bonded across its first two staking periods
• 493M $STX staked following PoX-5
• Zest: $122M in deposits and $42M in borrowing
These are reported milestones rather than current live balances.
Zest is particularly relevant because borrowing activity gives us something beyond deposit growth to measure.
The question is whether demand for $BTC-backed credit can expand without depending heavily on incentives.
➌ Security complicates BTCFi's expansion
Bitcoin holders value custody and security. Additional yield isn't necessarily attractive if accessing it requires taking significant bridge or counterparty risks.
Babylon uses Bitcoin-native time-locks for staking.
@Stacks and @rootstock_io support financial applications through different architectures, each introducing its own security assumptions.
Making $BTC productive is one challenge. Doing it without compromising the properties holders value is another.
➃ What deserves attention next?
I'm watching three indicators:
→ Borrowing demand relative to deposited collateral.
→ Trading fees and revenue generated without temporary incentives.
→ Institutional access to BTC-backed lending with reliable custody and liquidation mechanisms.
These should tell us more about BTCFi's development than TVL growth alone.
✦ My conclusion:
Bitcoin doesn't have a shortage of capital.
What BTCFi still needs to demonstrate is how much of that capital can support recurring financial activity.
Babylon has shown that billions can be attracted into staking. Lending protocols and financial applications now need to demonstrate sustained demand.
I'd rather see $1B supporting meaningful financial activity than $5B sitting in protocols with limited utilization.
That's the distinction I'll be paying attention to.

BLAZE retweeted

Hey friends, @grvt_io completed its first 1.1M GRVT buyback and burn. Now I’m looking at the next part of Grvt 2.0: what earning yield while trading could actually change for a user.
A few things stand out:
• Capital could keep earning while you wait for an entry.
Keeping funds ready for a trade often means leaving them idle. Grvt’s planned Yield as Margin feature would let eligible Earn balances continue generating yield while backing trading positions. That could reduce the need to move money between separate earning and trading products.
• The source of the yield matters.
The upgraded Grvt Earn is targeting up to 11% APY through tokenized fixed-income opportunities, with potential returns coming from underlying cash flows such as interest, premiums and invoices. The rate isn’t guaranteed; understanding the assets behind it matters as much as the headline percentage.
• More people could access institutional investment strategies.
Grvt aims to bring opportunities traditionally associated with banks and institutional investors to everyday users. Grvt puts the global fixed-income market at around $160 trillion; its ambition is to make a share of those opportunities more accessible onchain.
• Earning and trading would sit alongside user control.
Grvt’s self-custodial approach is built around users controlling their assets through their own keys. That matters when combining financial products in one app, although it doesn’t remove investment, smart-contract or liquidation risks.
The announced rollout places upgraded Earn in late October and Yield as Margin in November. Grvt already offers yield on collateral through Earn on Equity; the next step is extending that connection to eligible balances in the new Earn product.
The practical advantage I’m most interested in is having more flexibility with the capital already allocated to trading. I’d still check collateral eligibility, withdrawal terms and how losses affect the balance. A position can lose more than its collateral earns.
If Grvt delivers this well, waiting for a trade could become a more productive part of the trading process.
grvt.io/
🤝 Paid partnership


Hey friends, I wanted to take a closer look at @grvt_io’s 1.1M token buyback and burn, especially how we can check it for ourselves.
1.1 million GRVT bought back and permanently burned. @grvt_io has completed its first round, representing 0.96% of circulating supply at the time of purchase.
When I read a buyback announcement, my next question is usually: where can I check what actually happened?
Grvt’s public dashboard gives that question somewhere to go. It tracks the amount purchased, the percentage of circulating supply, cumulative burns and transaction hashes. Those hashes matter because they let readers follow the underlying onchain record beyond the numbers displayed on a page.
There’s a distinction worth checking along the way. Purchasing tokens and keeping them in a wallet leaves someone able to move or spend them later. Grvt states that these tokens were destroyed using the contract’s burn() function, permanently reducing total supply.
For me, the useful part is having a record to return to. If another round happens, I can compare how much was purchased, what was burned and how the cumulative total changed.
Future buybacks are intended monthly and remain at the token issuer’s discretion. Their timing and size can vary, so I’d assess each completed round on its own evidence.
This is the opening milestone on the road to Grvt 2.0, which aims to bring earning and trading together through one self custodial balance. As those products arrive, I’ll be looking for the same clarity: what has shipped, what remains planned and what users can verify themselves.
grvt.io/exchange/buybacks

BLAZE retweeted

ethereum privacy is moving beyond hiding transactions
but it has yet to prove that private finance can become an everyday experience
today, the ecosystem spans mixers, shielded balances, confidential assets, and privacy-focused applications
the capital shows demand:
→ @TornadoCash: $629.7M on Ethereum
→ @RAILGUN_Project: $109.7M
→ @0xprivacypools: ~$9.3M
→ @zama: ~$127M tracked under privacy
but TVL measures capital held, not private financial activity
from mixing to ongoing privacy
Tornado Cash lets users deposit, mix, and withdraw to fresh addresses
Railgun enables shielded balances, private transfers, and DeFi interactions through integrations involving Uniswap, Morpho, and Aave-style lending
its reported metrics include $5B+ cumulative private volume, ~$370K in 30-day fees, and nearly $14M in cumulative fees
the shift is from breaking transaction links to using shielded capital in financial activity
however, timing, withdrawals, public contracts, and user behaviour can still expose links
making privacy accessible
Ethereum Foundation’s Kohaku aims to integrate privacy tools into existing wallets
ERC-5564 defines stealth addresses, while ERC-6538 provides a registry for related metadata. @fluidkey and @UmbraCash use stealth-address functionality for private receiving
but private receiving doesn’t guarantee private spending
Privacy Pools explores screened privacy through association sets, with reported v2 features including private transfers, payment requests, LI.FI swaps, and Aave yield opportunities
its reported rollout spans Ethereum, Arbitrum, Base, Optimism, BNB Chain, Robinhood Chain, and Citrea
availability varies across networks and integrations
confidential finance
Zama develops confidential-token infrastructure designed to hide balances and positions. Reported confidential Morpho vaults exceed $100M, alongside swaps involving cUSDC and cUSDT
rather than relying only on shared pools, it brings confidentiality into existing financial infrastructure
other projects are filling gaps:
→ @zERC20io / @Veildotcash: unlinkable transfers
→ @Hinkal_protocol / @AnomaPay: private DeFi and payments
→ @ZKPanther / @PrivacyBoost: private trading and lending
→ @xochi_fi / @tacitfi: shielded settlement and issuance
→ @EkuboProtocol / @OpusMoney: private Starknet liquidity
→ @P_Inference: private AI payments
→ @raycashxyz / @Haven_Hn_: private financial applications
@aztecnetwork explores programmable private smart contracts on an Ethereum L2, while Hinkal explore shielded DeFi interactions
the remaining challenges
→ Small anonymity sets
→ Metadata and spending-pattern leaks
→ Complicated UX and fees
→ Limited liquidity
→ Unreliable integrations
→ Security and regulatory risks
one estimate puts private DeFi at ~0.02% of overall activity, though its methodology needs verification
zero-knowledge proofs provide strong privacy guarantees but cannot eliminate every information leak
what comes next?
Tornado Cash demonstrates demand for transaction privacy
Railgun pushes shielded balances toward active DeFi
Privacy Pools explores screened privacy, payments, and yield
Zama brings confidentiality to financial positions
Kohaku aims to improve access through existing wallets
these systems may complement one another rather than compete for the same TVL
the metric worth watching isn’t just how much capital gets shielded
it’s how much shielded capital gets transferred, swapped, lent, earns yield, or pays for something
that is the difference between privacy as a destination and privacy as a feature
i’m bullish on the infrastructure, but cautious about mass adoption
ethereum privacy is moving toward everyday finance
until private activity becomes simple, liquid, and accessible at scale, it remains promising infrastructure, not a proven everyday financial experience

BLAZE retweeted
big PnL screenshots usually get all the attention
but @agenticscredit just shared a more interesting stat 👀
the number of leaderboard traders above $1K PnL has nearly doubled in two weeks
to me, that's more useful than celebrating one standout account
it suggests the profitable group is getting wider
next I'd love to see their drawdowns alongside those gains
because a credit system needs to know not just who makes money, but how much risk they take
🤝 Paid partnership
