





Maximus retweeted

Implied volatility markets are not pricing midterm results to be a big event.
The forward volatility market is implying just a ~1.2% move in the S&P 500 Index tomorrow. That’s below what was implied one day ahead of 3 of the last 4 midterm elections. And it’s below what the S&P 500 realized after the 2018 and 2022 elections.

Maximus retweeted
Today marks only the 2nd day this year that retail investors have been net sellers.
MS QDS estimates, based on public data, that retail investors sold $1.4bn of US equities today — their first net sale since April. This is after retail has bought more than $1 trillion of ETFs and stocks YTD.

Maximus retweeted
The unwind in Hedge Fund equity exposures this year has been the biggest since at least 2017.
Active de-grossing (reduction in long + short positions) by global hedge funds has now hit over 8% of total gross exposure since June, according to the Morgan Stanley Prime Brokerage Content team.
This has taken gross leverage for US long/short funds down to the 10th percentile versus the last year.

In 1980, 90% of the trading volumes came from long term institutional investors and retail.
Today that number is down to 5-10% for II and 15% for retail.
About 50% of volumes come from actors that start and end the day flat.


Maximus retweeted

The PPI-CPI Gap Is Wide, and It Rarely Stays That Way
Producer prices are surging, and it’s unlikely firms can absorb this through margins.
Headline PPI +1.3% m/m, the strongest in 4+ years, and +6.4% y/y. Core PPI (ex food, energy & trade services) +0.5% m/m, +5% y/y, the fastest since 2022.
The PPI/CPI link is loose, but core PPI this hot rarely fails to pass through to core CPI.

ALT #inflation #macro #real estate #economy #fixed income #equities #fx #dollar #FedFund #mortagaes #Fed #ECB #BoE #BoJ #rates #volatility #TIPS #VIX #SuperCore #earnings #assets #liabilities #balance sheet #options #calls #puts #spreads #swaps #recession #gold #payrolls #unemployment #wages #fedfunds #silver #Trump #tariffs #Lutnick #Bessent #Warsh #S&P #Tech #Semiconductor #CPI #PPI
Maximus retweeted
At Morgan Stanley Equity Derivatives, deep, trusted, long-standing partnerships with the world's top investors are the hallmark of what we do.
Iliana Bouzali, Global Head of Derivatives Distribution and Structuring, sits down with legendary investor Stan Druckenmiller at the TomorrowX Summit on November 17-18 in Austin to explore macro, markets, the thinking behind the trades, and what the future may hold.

Taking the stage at @TomorrowXSummit: Stan Druckenmiller (@standuquesne), Chief Executive Officer of Duquesne Family Office, and Iliana Bouzali (@ilianabouzali), Global Head of Derivatives at Morgan Stanley (@MorganStanley) $MS.
November 17-18 at the Moody Center in Austin. Hosted with @GavinSBaker and @atreidesmgmt, @antoniogracias and Valor Equity Partners, @rbiscardi and @iconnections_io.
Registration link below.


Maximus retweeted
In an AI world, the most valuable investing skill will be … “creativity." Justin Lubell of @Citadel talks conviction and the role of human judgment. Watch his full Break the Playbook conversation with @MorganStanley Derivatives. mgstn.ly/4imYQgm
Maximus retweeted
The goal is “intellectual conviction as opposed to emotional conviction.”
@Citadel’s Justin Lubell joins Break the Playbook to discuss finding top talent, backing ideas with intellectual conviction, and why investing remains a deeply human business.
Watch the trailer:

Maximus retweeted
The rally in S&P 500 has the index hitting the peak dealer gamma wall of $24bn near 7845 in spot, per MS QDS.
But much of that dealer long gamma expires today. Absent new customer supply, that stabilizing force gets smaller, leaving the market freer to move.
I don't see the appeal of the long bond trade.
Surely if yields stabilize or fade from here, there are better plays in beaten down equities no?
Feels like a mis-allocation of capital.
Maximus retweeted
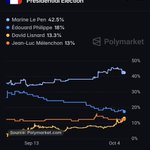
Thank you for this. However I would caution against falling in the easy “Le Pen vs Melenchon” narrative which is not representative of what the betting markets are telling us.
David Lisnard has been making huge strides lately and is fiscally very conservative/responsible. He’s the French Milei (and so is @knafo_sarah but unfortunately she is not running).
He’s just not polled (yet) bc started from too low.

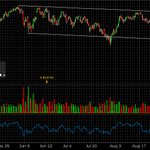
A small bull flag (In red in the chart below) sitting above the breakout of a much larger bull flag (in white) tends to represent acceptance of the breakout rather than exhaustion.
However, the small flag often isn't resolved cleanly. Markets frequently produce downside probes, retests of the breakout level, or several weeks of frustrating sideways action before continuing higher.
The important warning signal isn't simply the small flag breaking slightly downward. It's price moving materially back into the large prior consolidation and remaining there. That changes the historical character of the setup substantially.
So:
Large breakout → small consolidation above old resistance → bullish
Temporary undercut/retest → rapid recovery → still generally constructive
Sustained move back inside the old large flag → significantly weaker setup / possible failed breakout
The location of the small flag relative to the major breakout level therefore appears more informative than the precise shape of the small flag itself.
Recent occurrences studied:
NDX 2016–17 (bullish), NDX October 2017 (bullish), SPX 2016 (bullish), 2019 (failure), SPX/NDX 2024 (bullish)
$QQQ $SPY $SPX $ES $NQ $ES_F $NQ_F
Credit to ChatGPT

Maximus retweeted

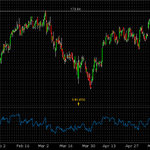
1/ There's a scary chart going round on X: junk bonds ($HYG) at a 52-week low while $SPY sits 1.4% off its record.
Scary, because credit markets are usually much better at sniffing out trouble than equity markets.
Anyway, I pulled it apart.
BlackRock runs a version of $HYG with the Treasury risk hedged out ($HYGH). Over the past year HYG is down 4.1%. HYGH is down 0.4%.
So about 90% of HYG's damage came from duration. The part that prices default risk has barely moved, and junk spreads sit 13bp from 3-year tights
So the scary chart is mostly bond maths. The basement of the junk bond market is a different story however 👇🏻

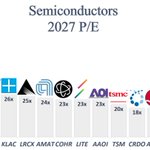
E.g. “it’s very positive for CPUs, hence $INTC.
Intel is trading at 53x already. Are you sure it’s not priced in already?


Seeing a lot of comments over the last few days on Muse, CPU demand etc…
One has to make a distinction between a brand new technology/innovation the market hasn’t priced yet, and a brand new technology/innovation we knew was coming and stocks already anticipated.
We knew agents were coming. Remember OpenClaw?
Sure, Muse/Instinct are better.
But it’s not because Audi releases a new better model that the car industry will rip.
I don’t have the answer to my question (yet), but before you get excited about this and that stocks, ask yourselves what were those stocks pricing before.
Seeing a lot of comments over the last few days on Muse, CPU demand etc…
One has to make a distinction between a brand new technology/innovation the market hasn’t priced yet, and a brand new technology/innovation we knew was coming and stocks already anticipated.
We knew agents were coming. Remember OpenClaw?
Sure, Muse/Instinct are better.
But it’s not because Audi releases a new better model that the car industry will rip.
I don’t have the answer to my question (yet), but before you get excited about this and that stocks, ask yourselves what were those stocks pricing before.