

«All of humanity’s problems stem from man’s inability to sit quietly in a room alone» | Value | Special Sits | Global Equities | 23
Stockholm, Sweden
Joined November 2020
- Tweets1.8K
- Following206
- Followers1.7K
- Likes17.4K



Pinned Tweet
Planned a tweet, but had too much to say on $EVC.
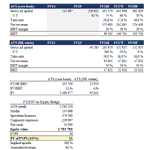
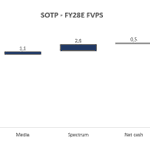
ATS growth went from +123% to +230% (4Q25 to 2Q26) and EBIT >tripled, yet the EBIT multiple fell from 21x to ~5x (ex media+spectrum) w/ px up just 53%. New CMO, 2 new directors and a strong ranking add to the case.
Link in bio!

TheOracleOfOslo retweeted

Audited track records are mostly non-existent, but you can scroll through the leaderboard for a lot of examples of good investors: joinyellowbrick.com/leaderbo…
Besides the ones you mentioned, @AurelionRsch, @irbezek, @SebKrog, @HugoNavarroPer2, @Floe_FS , @Kreuzmann13, @peter_mantas, @MikeFritzell, @ppinvest, @uv_shares, @siyul, @finphysnerd, @Atrium_Research, @AltayCapital, @ragingbullcap, @LuxOpesResearch, @Petty__Cash, @agnostoxxx, @scuttleblurb, @everyonehatesp1, @BuffDawgg. Some newer guys like @thegresearch are promising
I'm surely missing some. @evfcfaddict knows all the good europoors if I'm missing any.

Quick reversal! C will keep negotiating on S’s package, but V won’t budge on ministerial posts, and C seems firm on its friskolor stance.
I’m wondering whether the Nyköpings LOI $CEDER announced today is about waiting for clarity on the government formation to get a lower price.


$CEDER +20% in a month as Kristersson becomes the favorite for PM. Direct RE ownership diversifies political risk, K3 to IFRS should improve screening, and a main listing opens up institutional capital. Based on the guided FY27 floor, you’re paying sub 6x EBITA here.


15
1,379
You don't say

Nvidia’s board of directors is not considering bringing back Jensen Huang as CEO, a person familiar with the matter told CNBC. The board is focused on a national security investigation into Huang, and is not in discussions to bring him back, the person said.
cnbc.com/2026/11/16/nvidia-c…

4
702
$GRVY Q3 print: rev of KRW 197.1bn (+42% Y/Y) and EBIT of KRW 28.7bn (+35% Y/Y, 14.6% margin). Mgmt is targeting double-digit rev growth and, more interestingly, setting a PO ratio of >10% of net income, suggesting dividends will be recurring. Still at sub 0.5x LTM EBIT here...


$GRVY trades at sub 1x EBIT despite a loaded pipeline, aligned insiders at the majority shareholder, and a dividend that disproves the cash hoarding narrative. Backed by ample cash and a beloved IP, a meaningful payout should close the gap to dividend-paying peers. Link in bio!


I think $TERNOR should have made a bigger number out of this, but they reclassified changes in WC starting in 1Q26. On the old CF layout it looks like there’s no WC release in Q4, but restated it’s +126m. The APM table (using balance sheet NWC) shows +124.5m too


$TERNOR Q3: rev SEK 931m (+17% Y/Y), adj. EBITA SEK 32m (3.4% margin, +80bps). On track for FY26 3.9% margin target as Q4 was 49-51% of adj. EBITA in ‘24-25. Backlog SEK 7.2b (+22%), order intake SEK 337m (+61%), and CMD targets reiterated. Stock still at ~5x my FY28e FCFF


$CEDER +20% in a month as Kristersson becomes the favorite for PM. Direct RE ownership diversifies political risk, K3 to IFRS should improve screening, and a main listing opens up institutional capital. Based on the guided FY27 floor, you’re paying sub 6x EBITA here.
TheOracleOfOslo retweeted

5 more I read and liked, all credited inside the issue.
🔹 Midwich Group ($MIDW.L): specialist AV distributor with a dominant UK position, priced at a cyclical trough with recent signs of organic growth. raut capital
🔹 DY Power ($210540.KS): Korean hydraulic cylinder maker with net cash at 4.2x earnings, waiting on Value-Up reforms to lift its payout from 25% toward 60%. Uncrowded Value
🔹 Entravision ($EVC): a fast-growing ad-tech arm, Smadex, inside a company the market still reads through its legacy media. @BuffDawgg
🔹 Nuvectis Pharma ($NVCT): 2 near-term catalysts, an FDA path for NXP100 and Phase 1b data for NXP200, while partner Haisco funds the large trials. Truffle Pigs
🔹 Jewett-Cameron ($JCTC): liquidation would return $6.75 a share against $2.72, through a new board elected to force it. Terry Schumacher
All 9 authors did the research and I only chose between them, so follow them ahead of me.
Link in the comments.
Using a/r and exit rate from the HK account as a proxy for spend (assuming unchanged payment terms), there was a pick-up at quarter-end (+10% vs. Q2), suggesting spend has either stabilized or is ramping. Also indicative of Smadex’s clients adjusting, rather than pulling spend.

$EVC Q3 print: ATS rev +133% yy (-3% seq) vs. guided floor of > 100% yy. Take-rate rose to 39.4% (38.8%), while the core book grew 68% yy and 19% seq. Concentration risk fell w/ the HK customer now = 30% of group rev. #2 whale now = 8% (+59% seq), and EVC sold 1 station for $30m.


15
1,158
$EVC Q3 print: ATS rev +133% yy (-3% seq) vs. guided floor of > 100% yy. Take-rate rose to 39.4% (38.8%), while the core book grew 68% yy and 19% seq. Concentration risk fell w/ the HK customer now = 30% of group rev. #2 whale now = 8% (+59% seq), and EVC sold 1 station for $30m.
Planned a tweet, but had too much to say on $EVC.
ATS growth went from +123% to +230% (4Q25 to 2Q26) and EBIT >tripled, yet the EBIT multiple fell from 21x to ~5x (ex media+spectrum) w/ px up just 53%. New CMO, 2 new directors and a strong ranking add to the case.
Link in bio!
ATS EBIT+margin fell q/q on sales, engineering and adops hiring plus a multi-cloud migration. Media’s Q3 was very weak (though political spend is mostly Q4), but the silver lining is that mgmt is exploring options for the TV stations, pointing to a partial media/ATS separation.

1
1
712

TheOracleOfOslo retweeted

After two decades helping grow some of the biggest names in gaming, from Angry Birds and Candy Crush to NBA 2K, Luis de la Camara is joining Smadex as our new Chief Marketing Officer!🎉
Read the full announcement 👉 lnkd.in/enKaaF-q
TheOracleOfOslo retweeted

Small Cap stocks don’t even try to go up anymore. They just look at you like this.

$EVC's TelevisaUnivision affiliation got a 3-month extension, w/ quarterly rolling. It provides some visibility, but reads like a stopgap while talks continue.
Maybe a bit far-fetched, but could TelevisaUnivision be eyeing EVC's TV stations now that the 39% cap is being lifted?


Small contract, but it ends a months-long silence. $HAV notes that scopes like this typically generate NOK 40-60m in revenue, and that engineering and procurement kick off this year.

1
17
1,327


On EVC, assuming the core book keeps compounding, a 64% drop in HK spend and 12/4x multiples = >3x. $HAV flipped in the q on weak order intake, but the asymmetric setup, promising mgmt commentary re the strategic review and better 2027 visibility by Q3 reinforce my conviction


8
992